

San Francisco is absolutely BREATHTAKING. If we are being honest, as a Photographer based here, I think that there are some of the best locations for scenic photos in the greater Bay Area!
I spend every day exploring these locations with my clients. If you don’t believe it, check out the following photos to see for yourself!
TOP #9 PHOTO LOCATIONS IN THE GREATER BAY AREA
#1: HALF MOON BAY
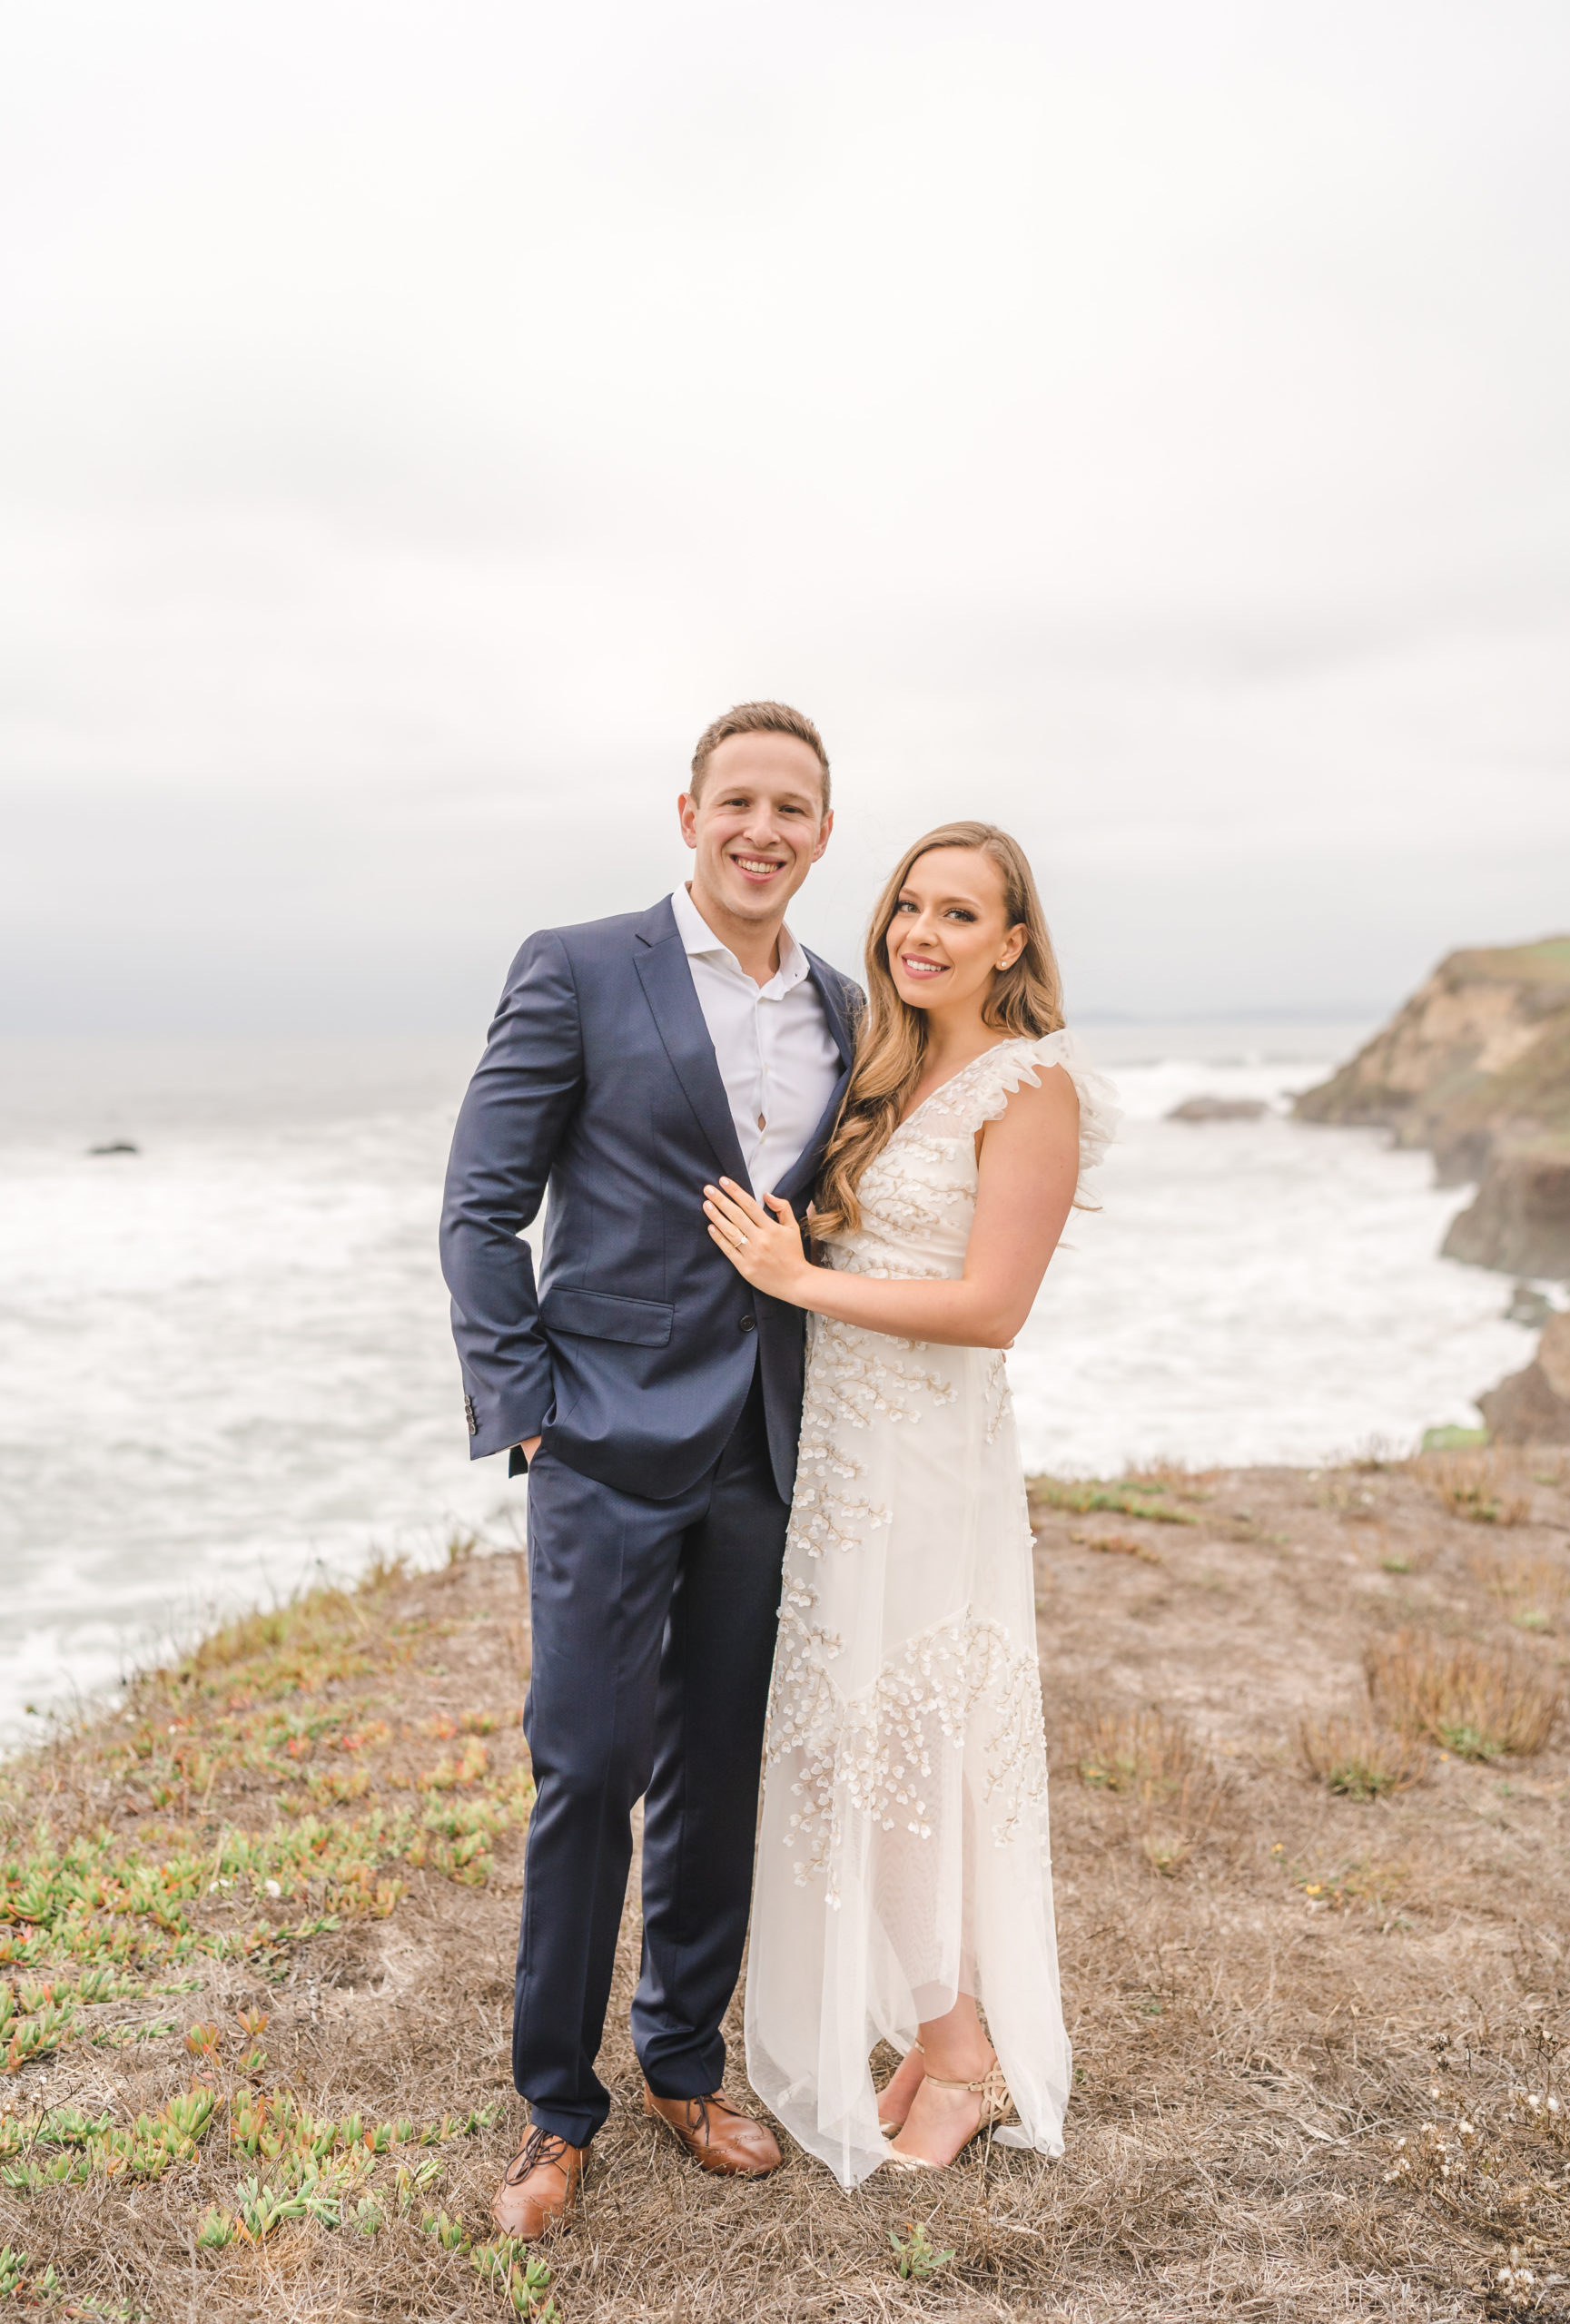
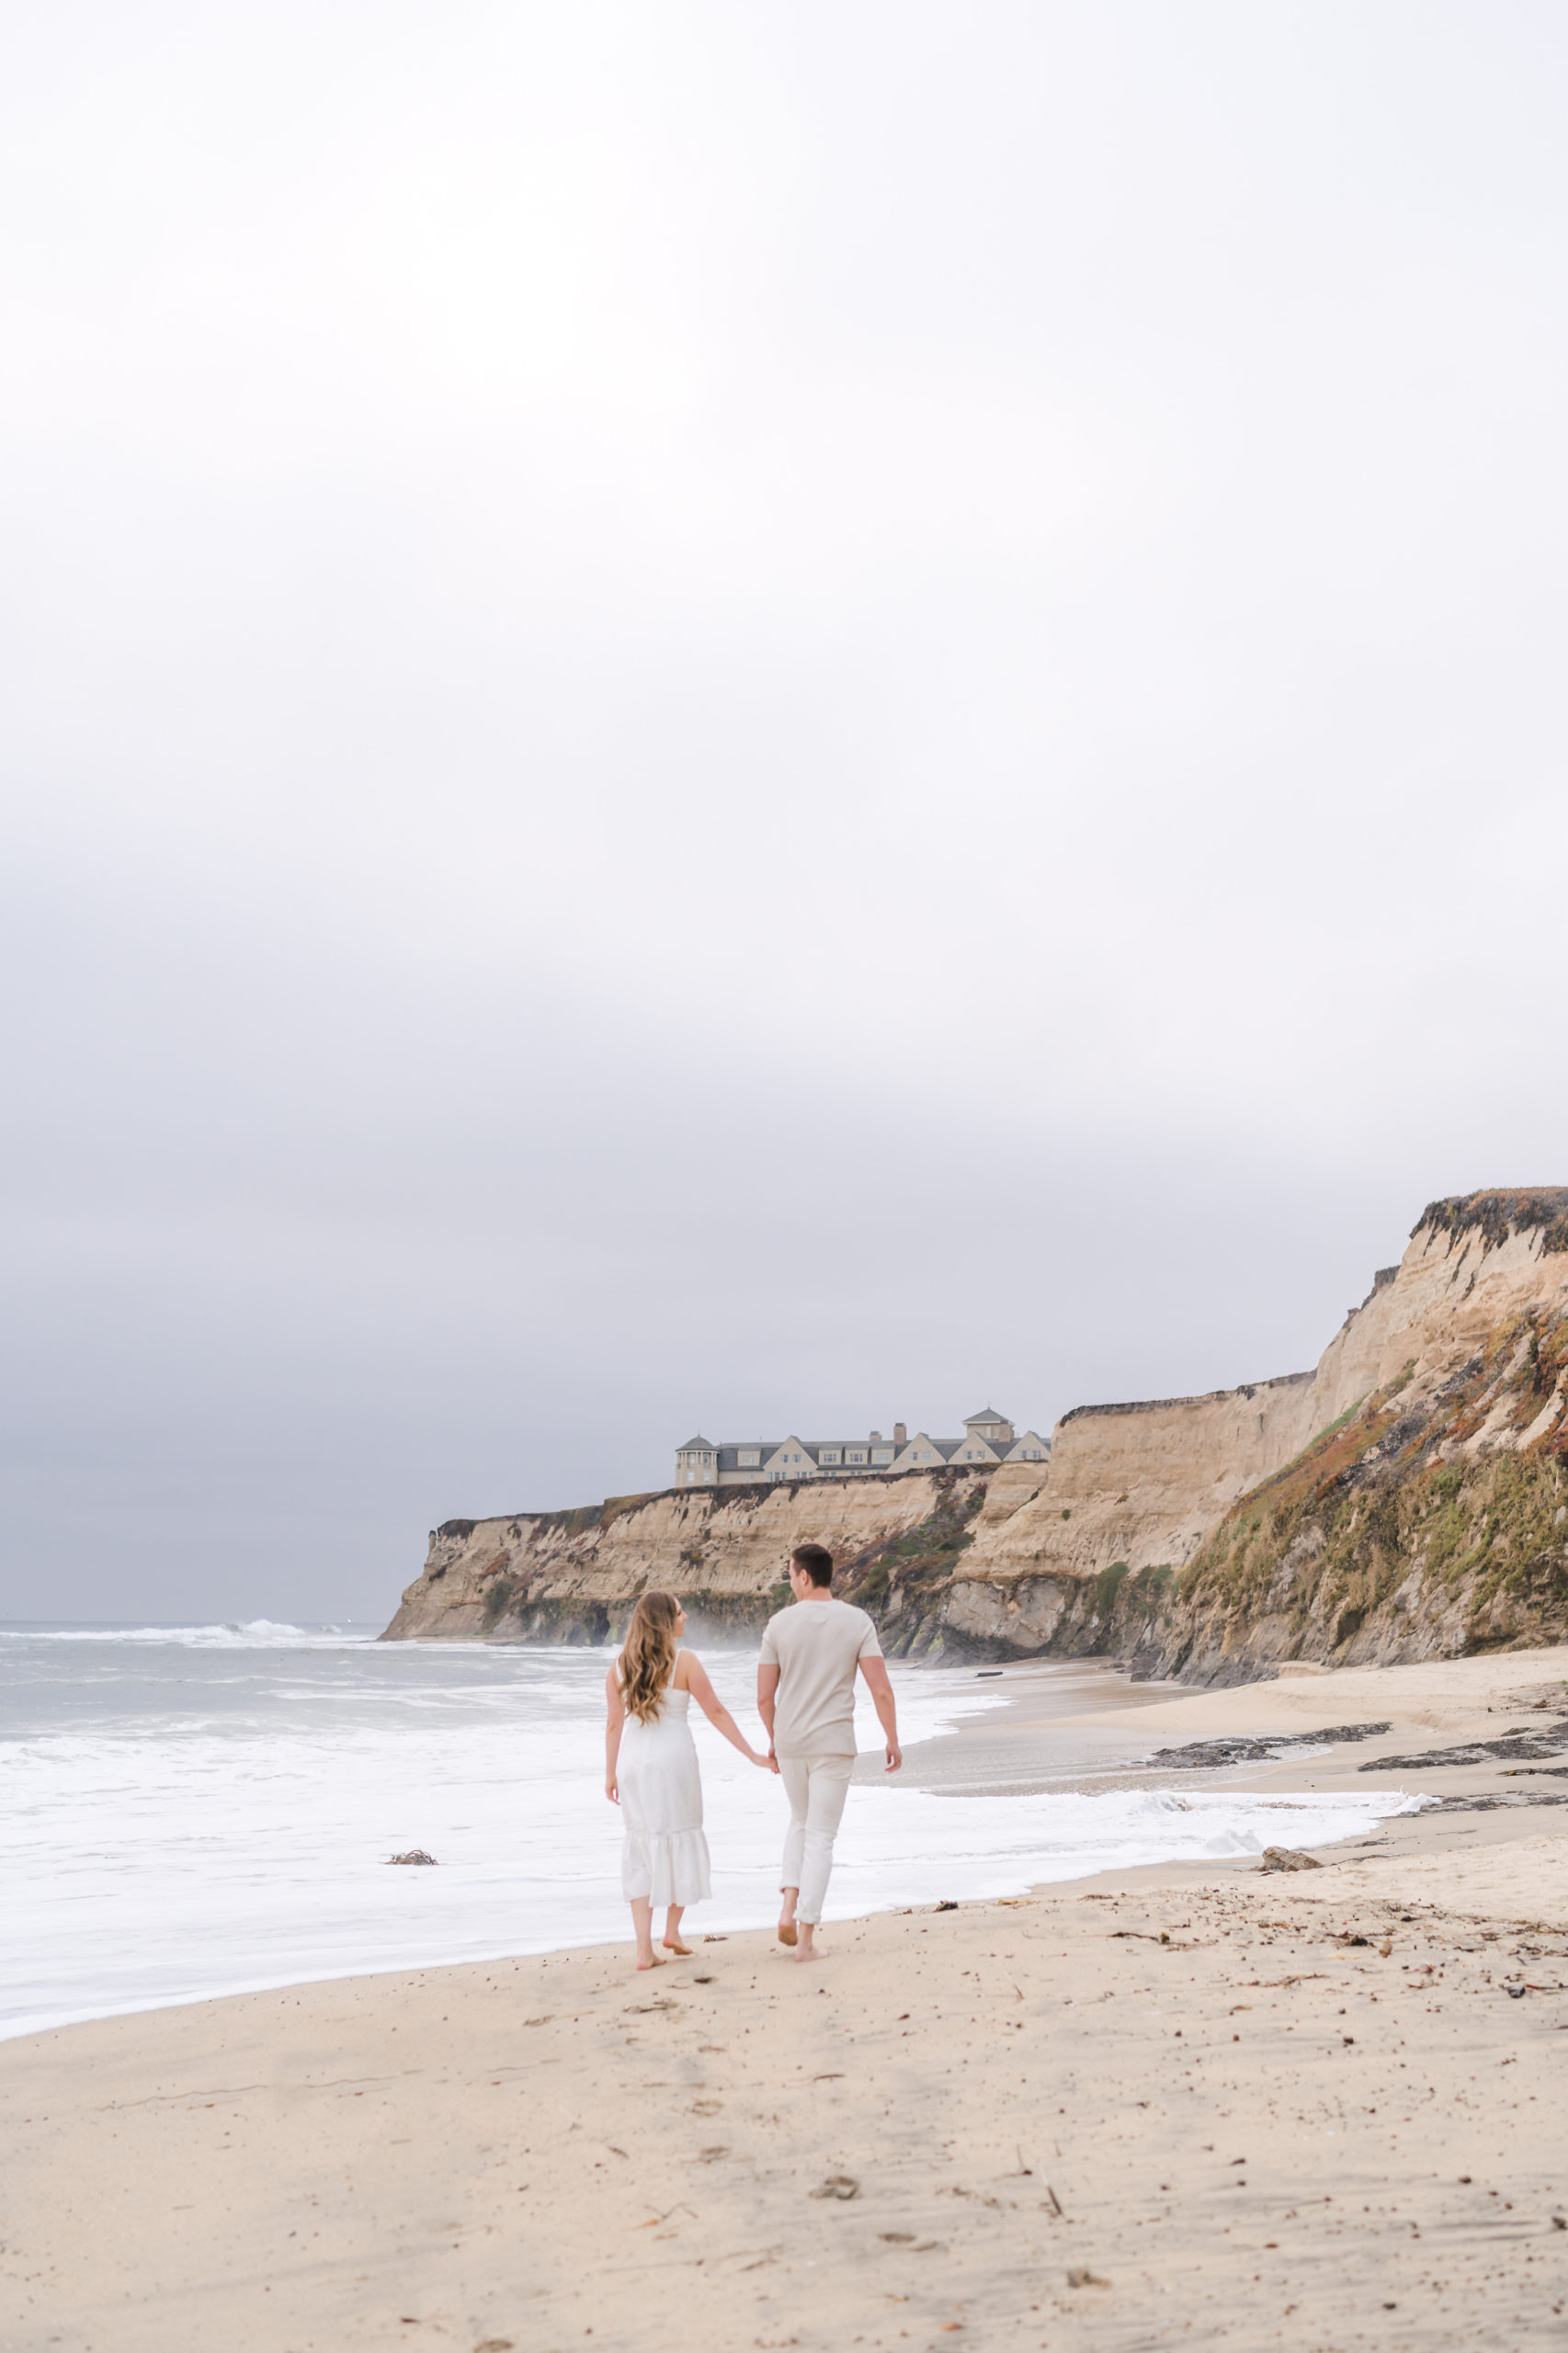

#2: BAKER BEACH

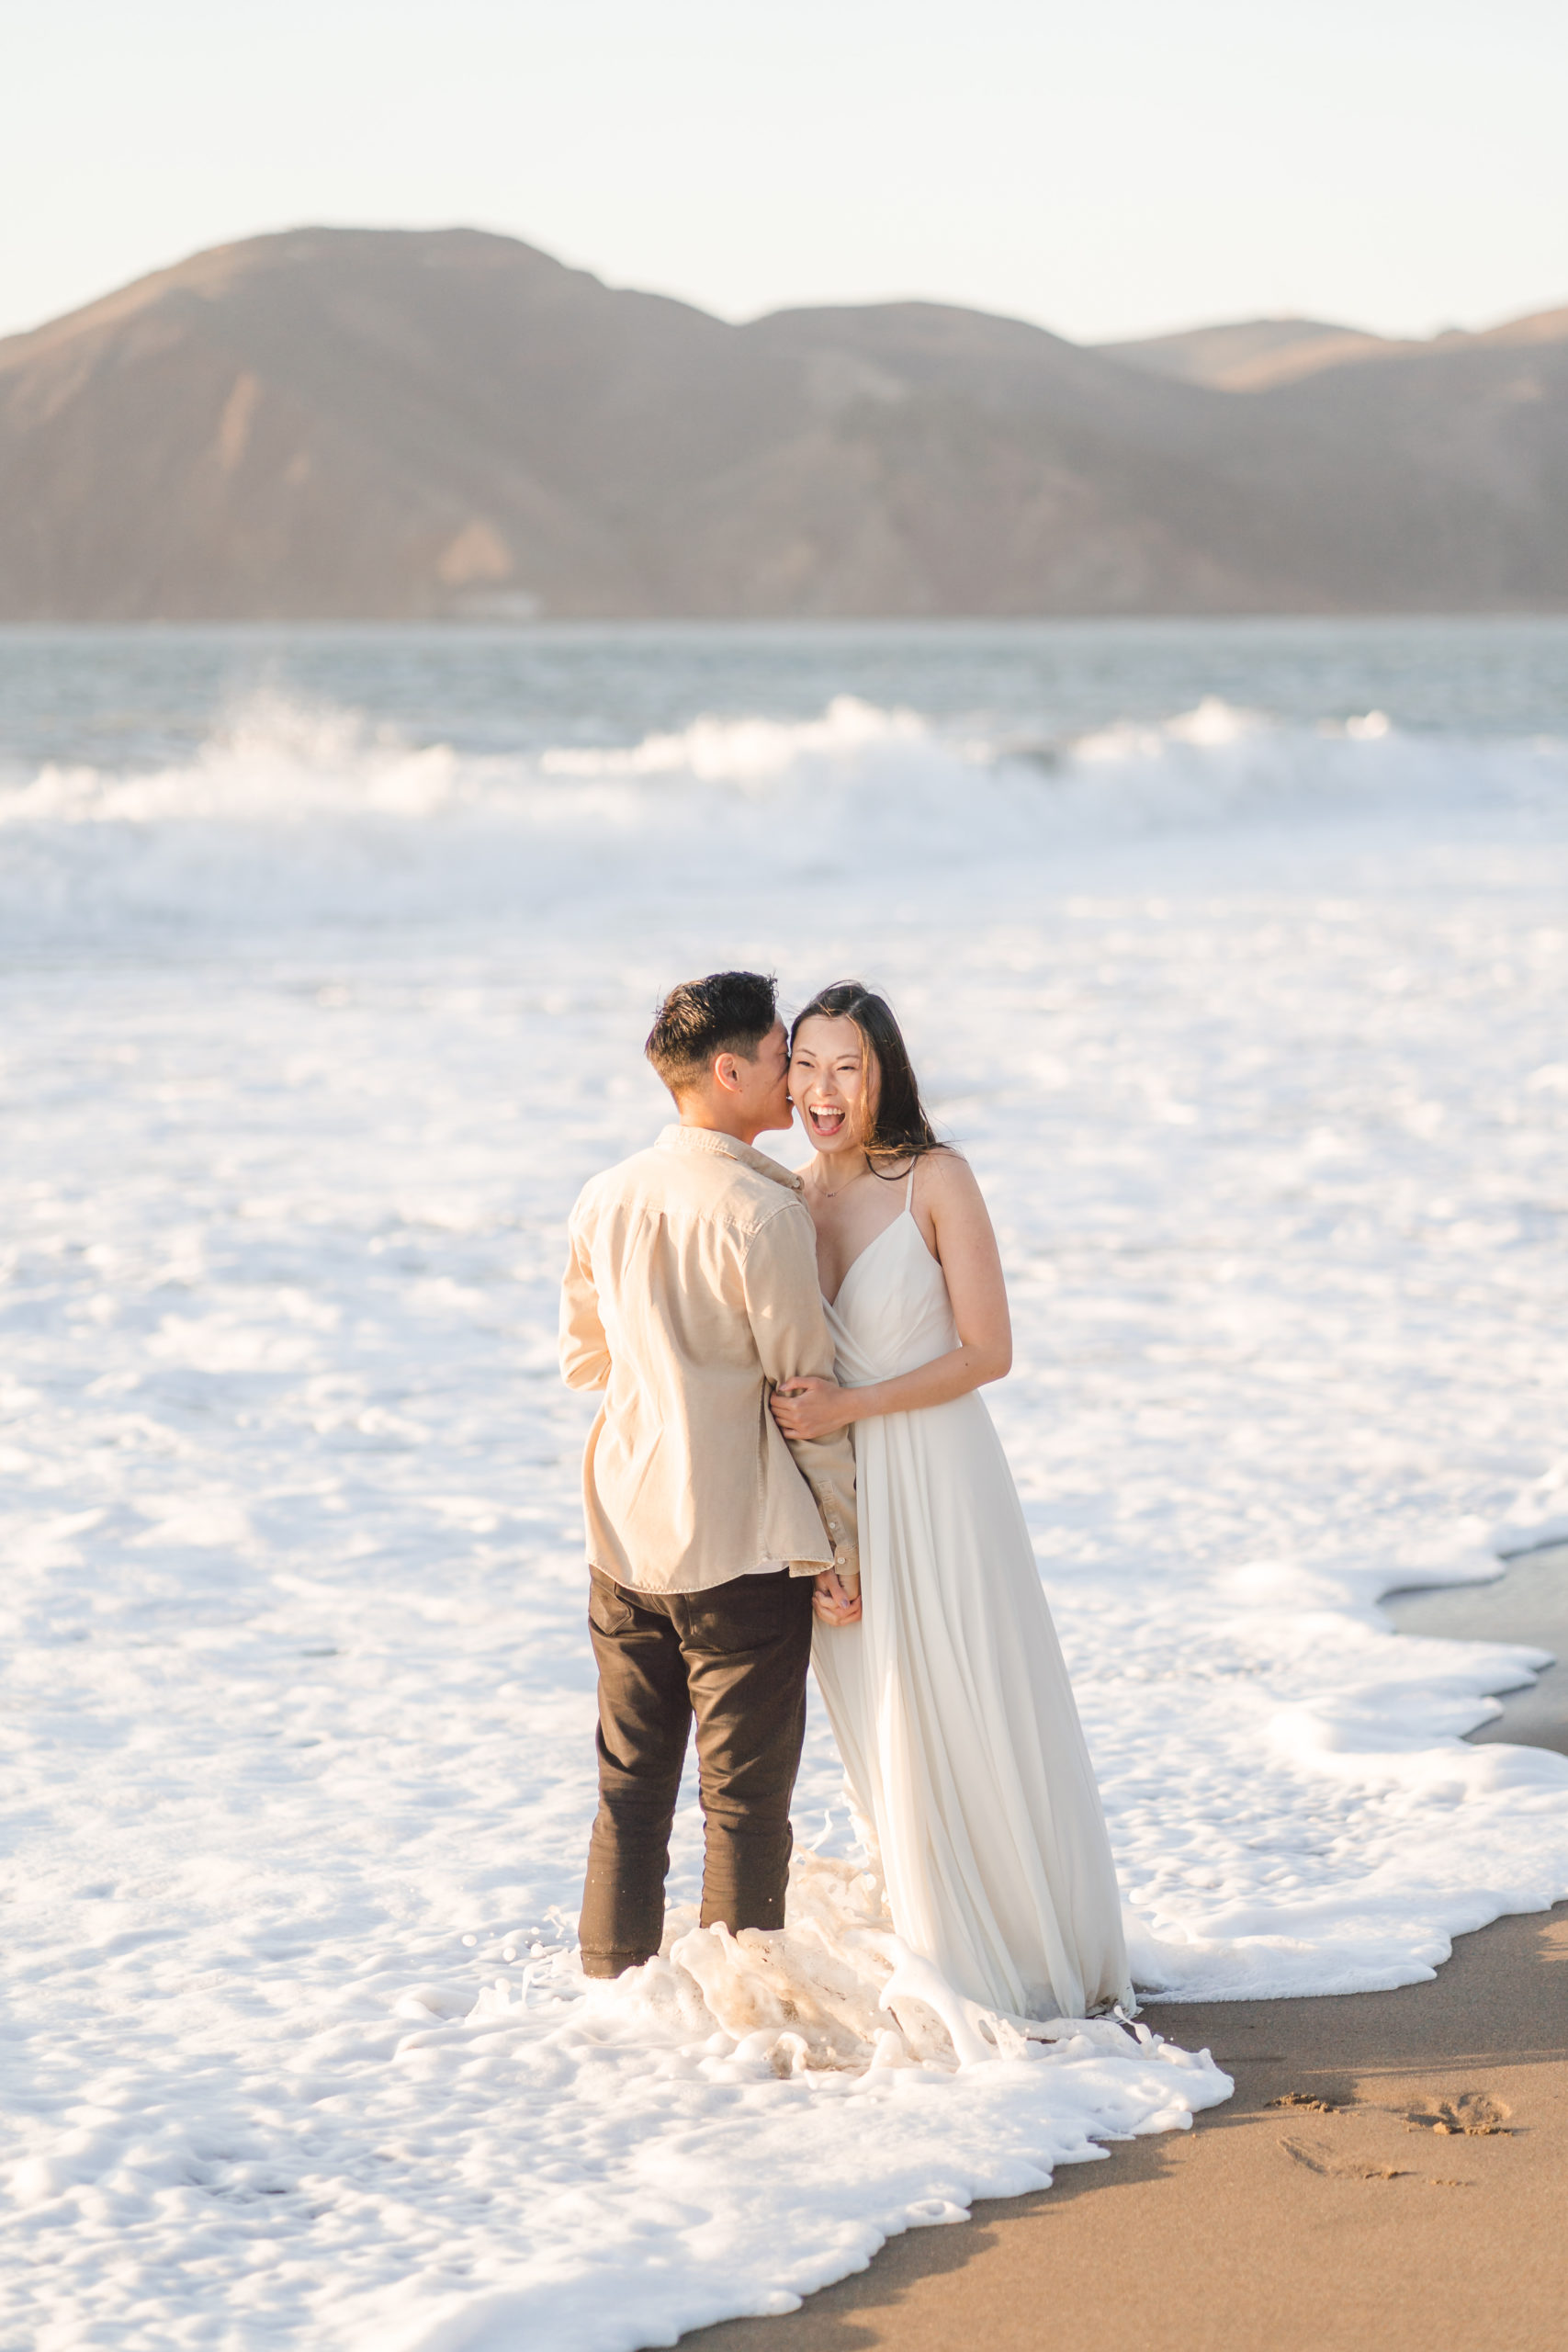

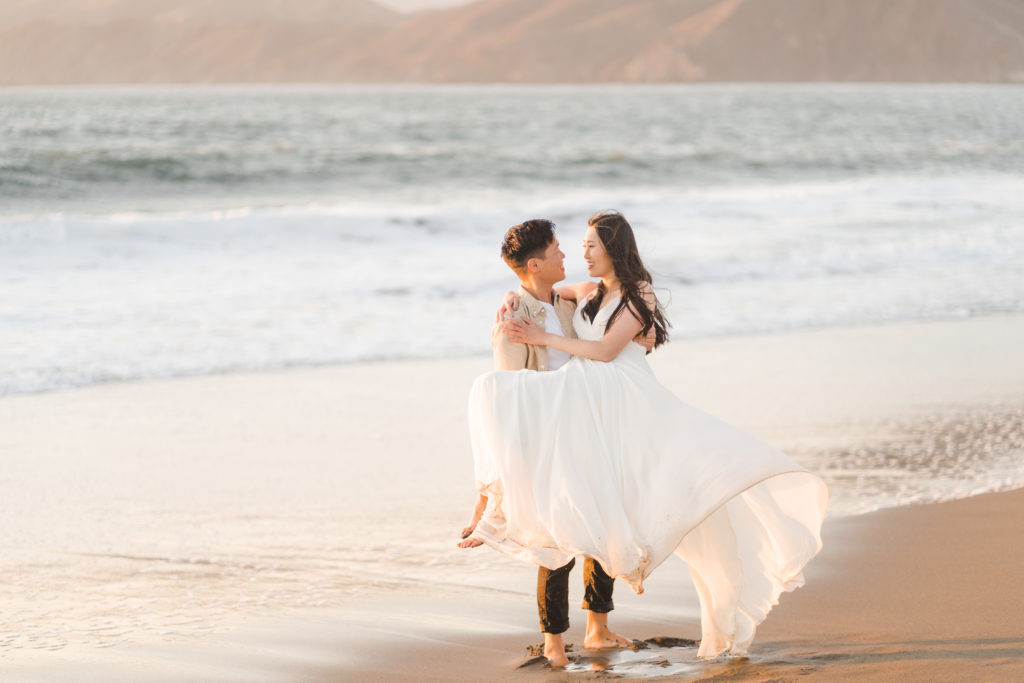
#3: SAN FRANCISCO CITY HALL


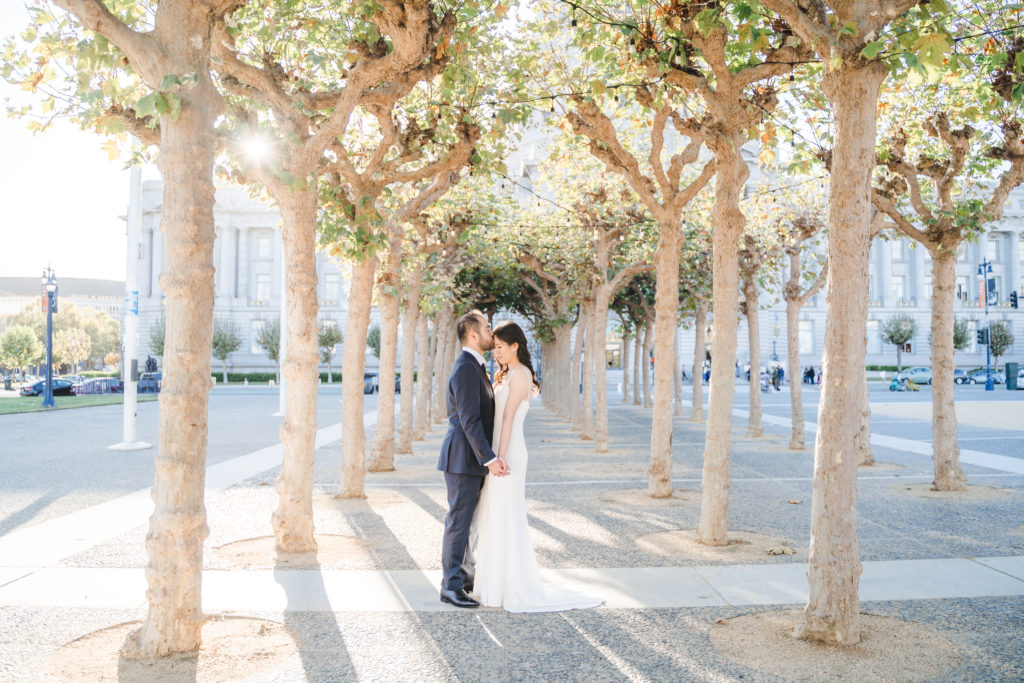
#4: FORT FUNSTON


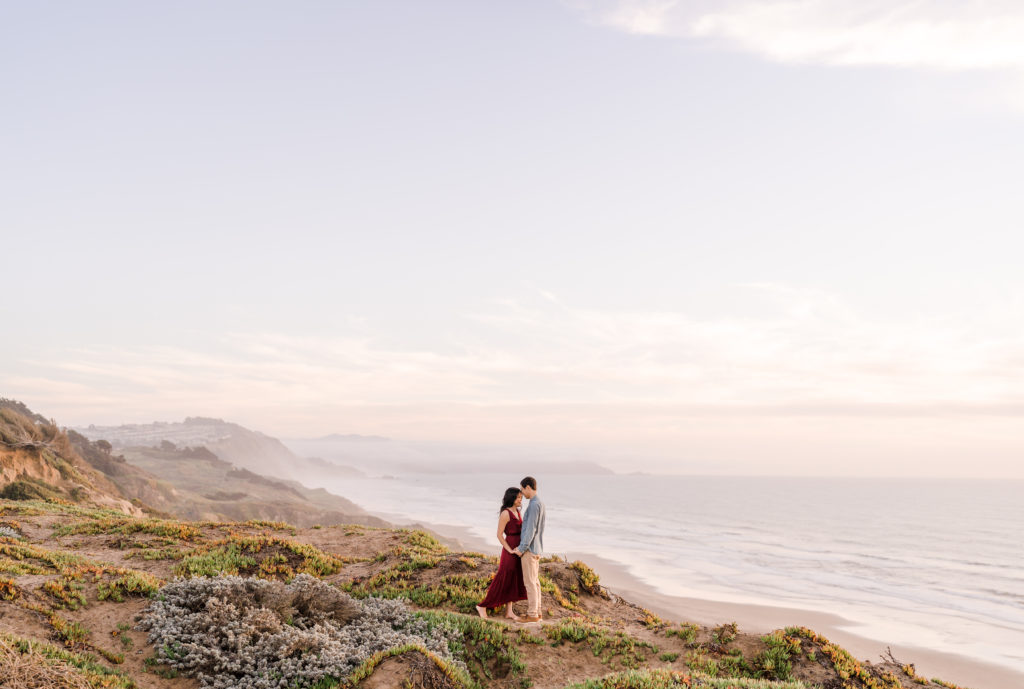
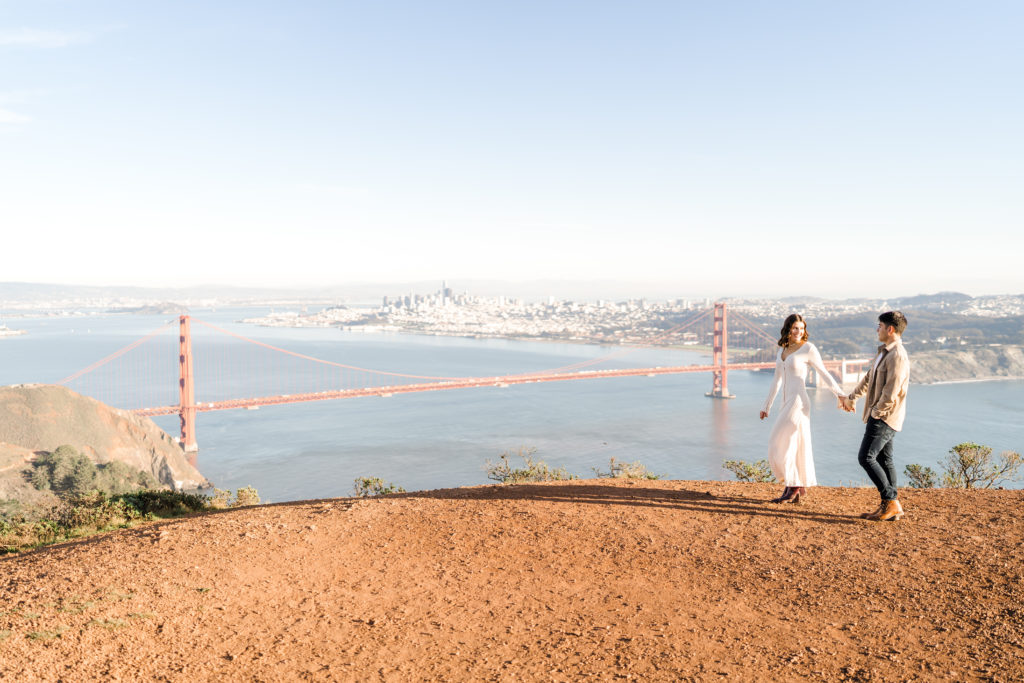
#5: MARIN HEADLANDS

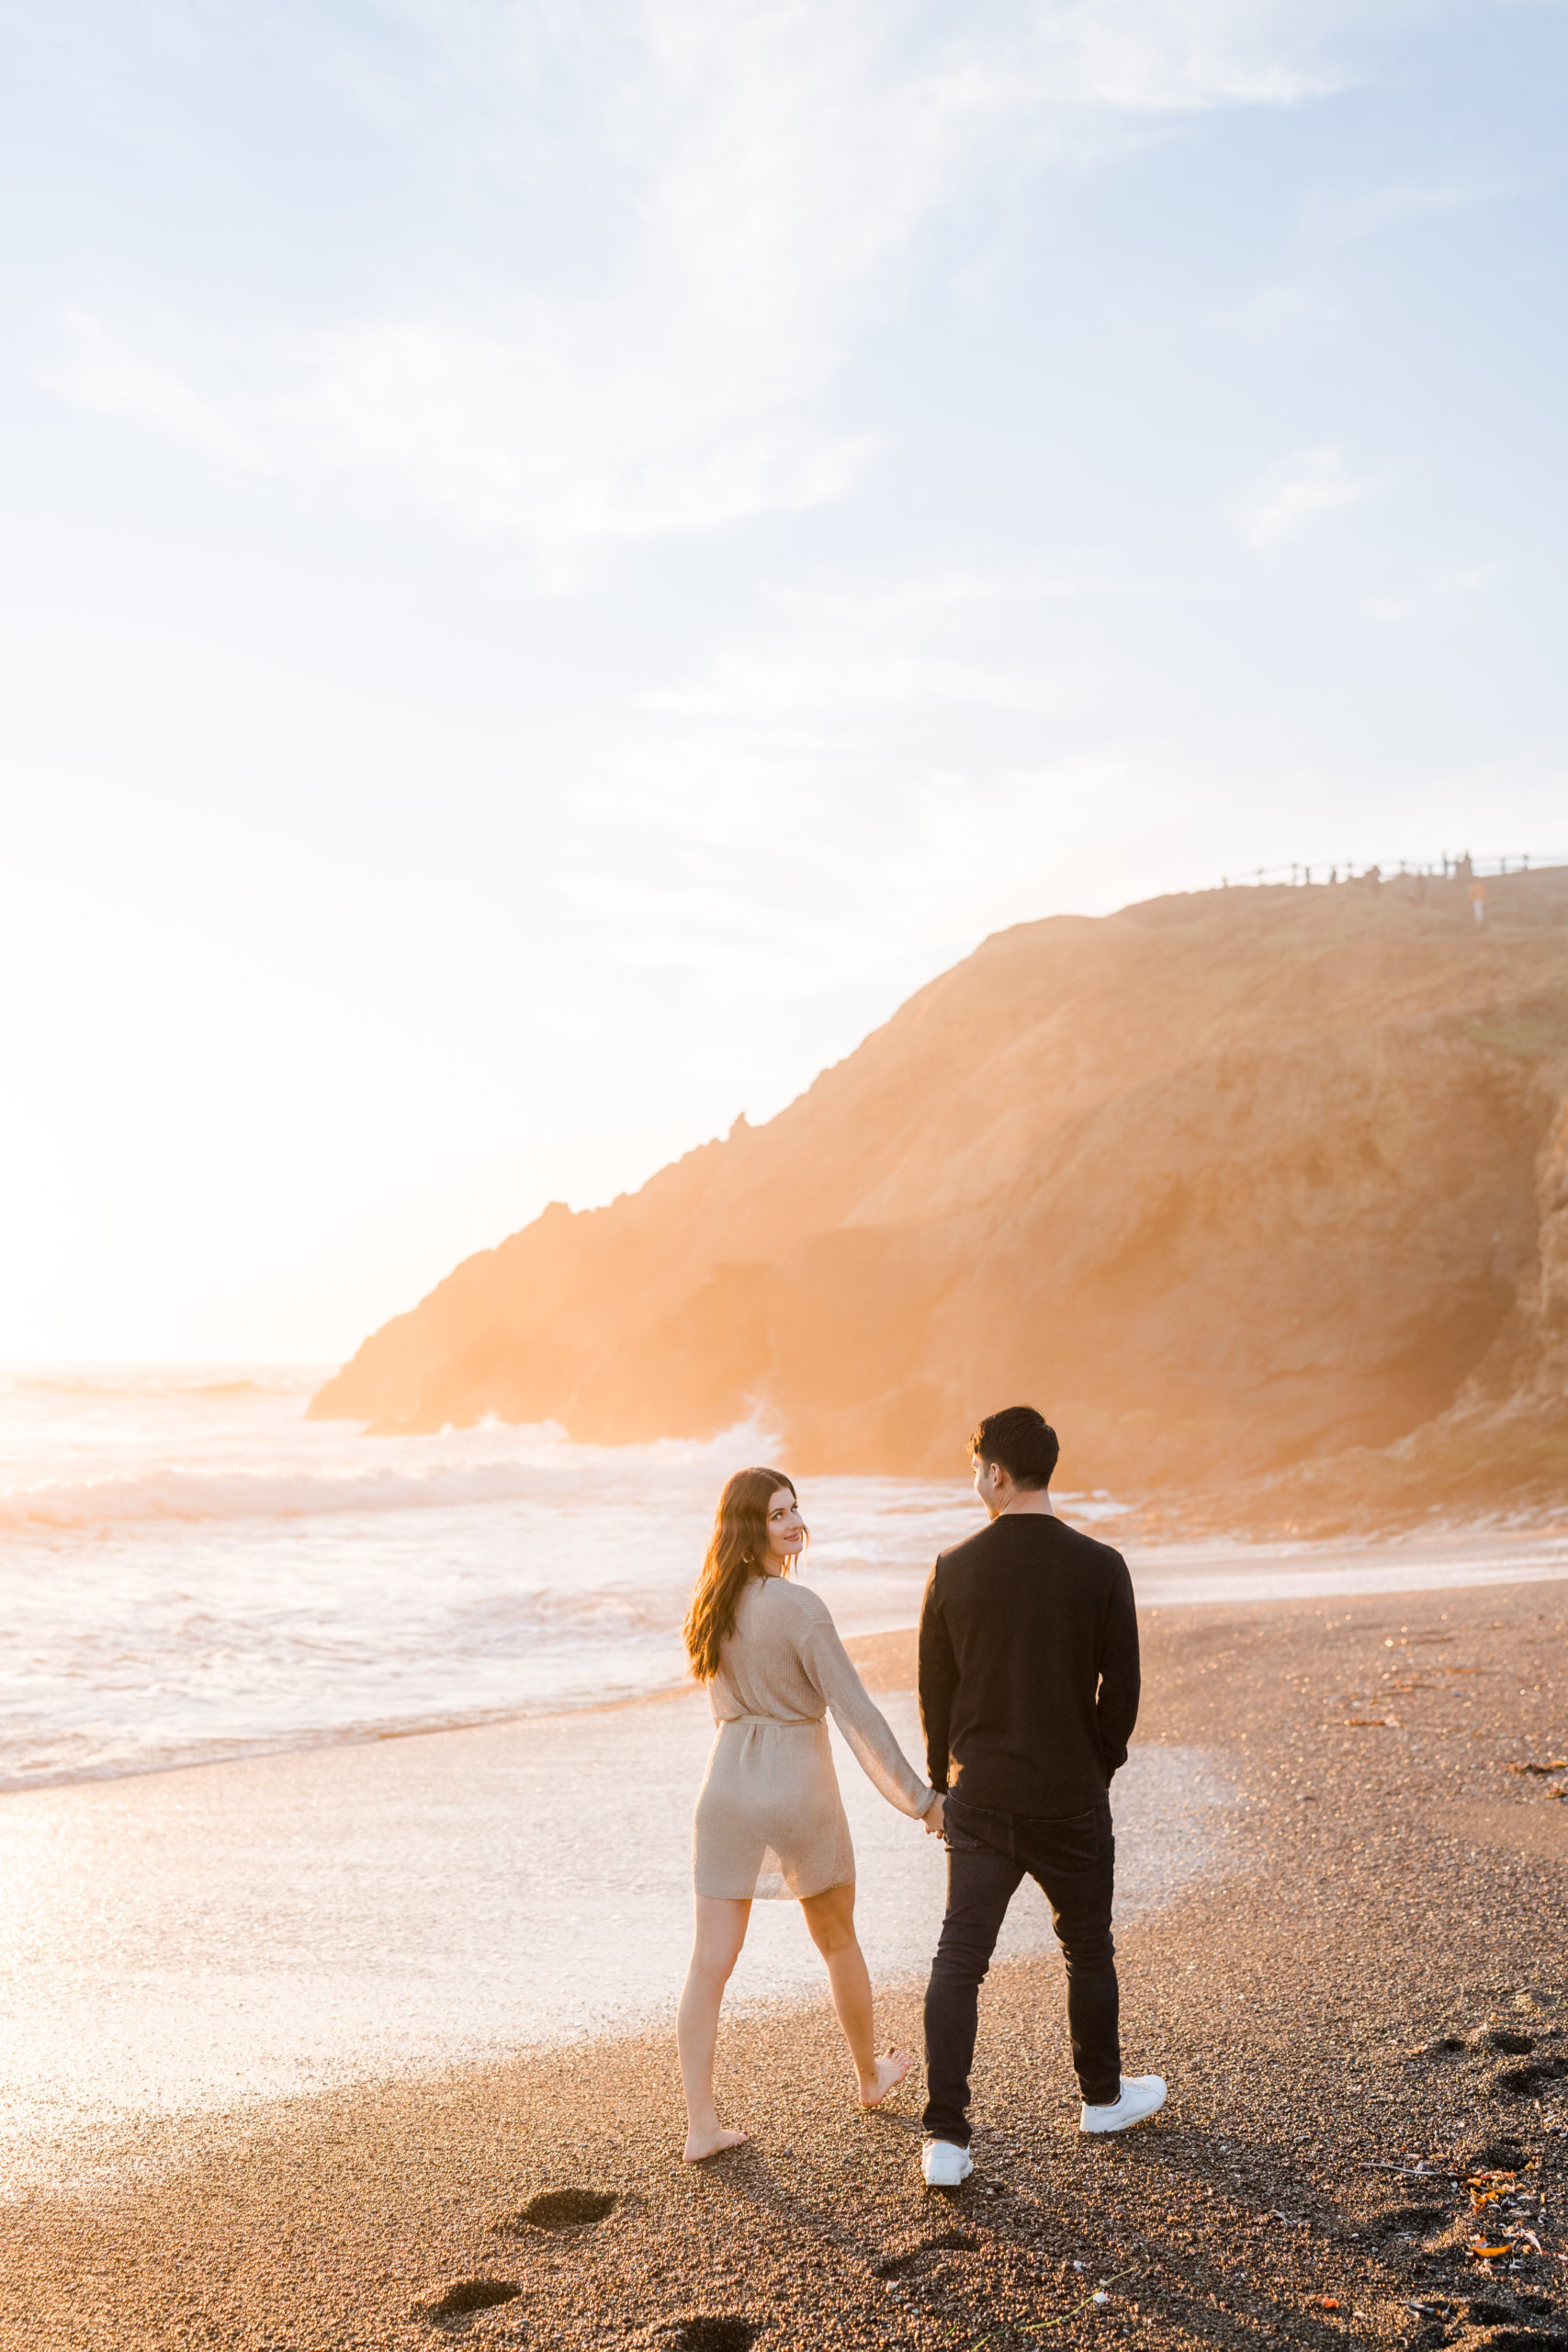

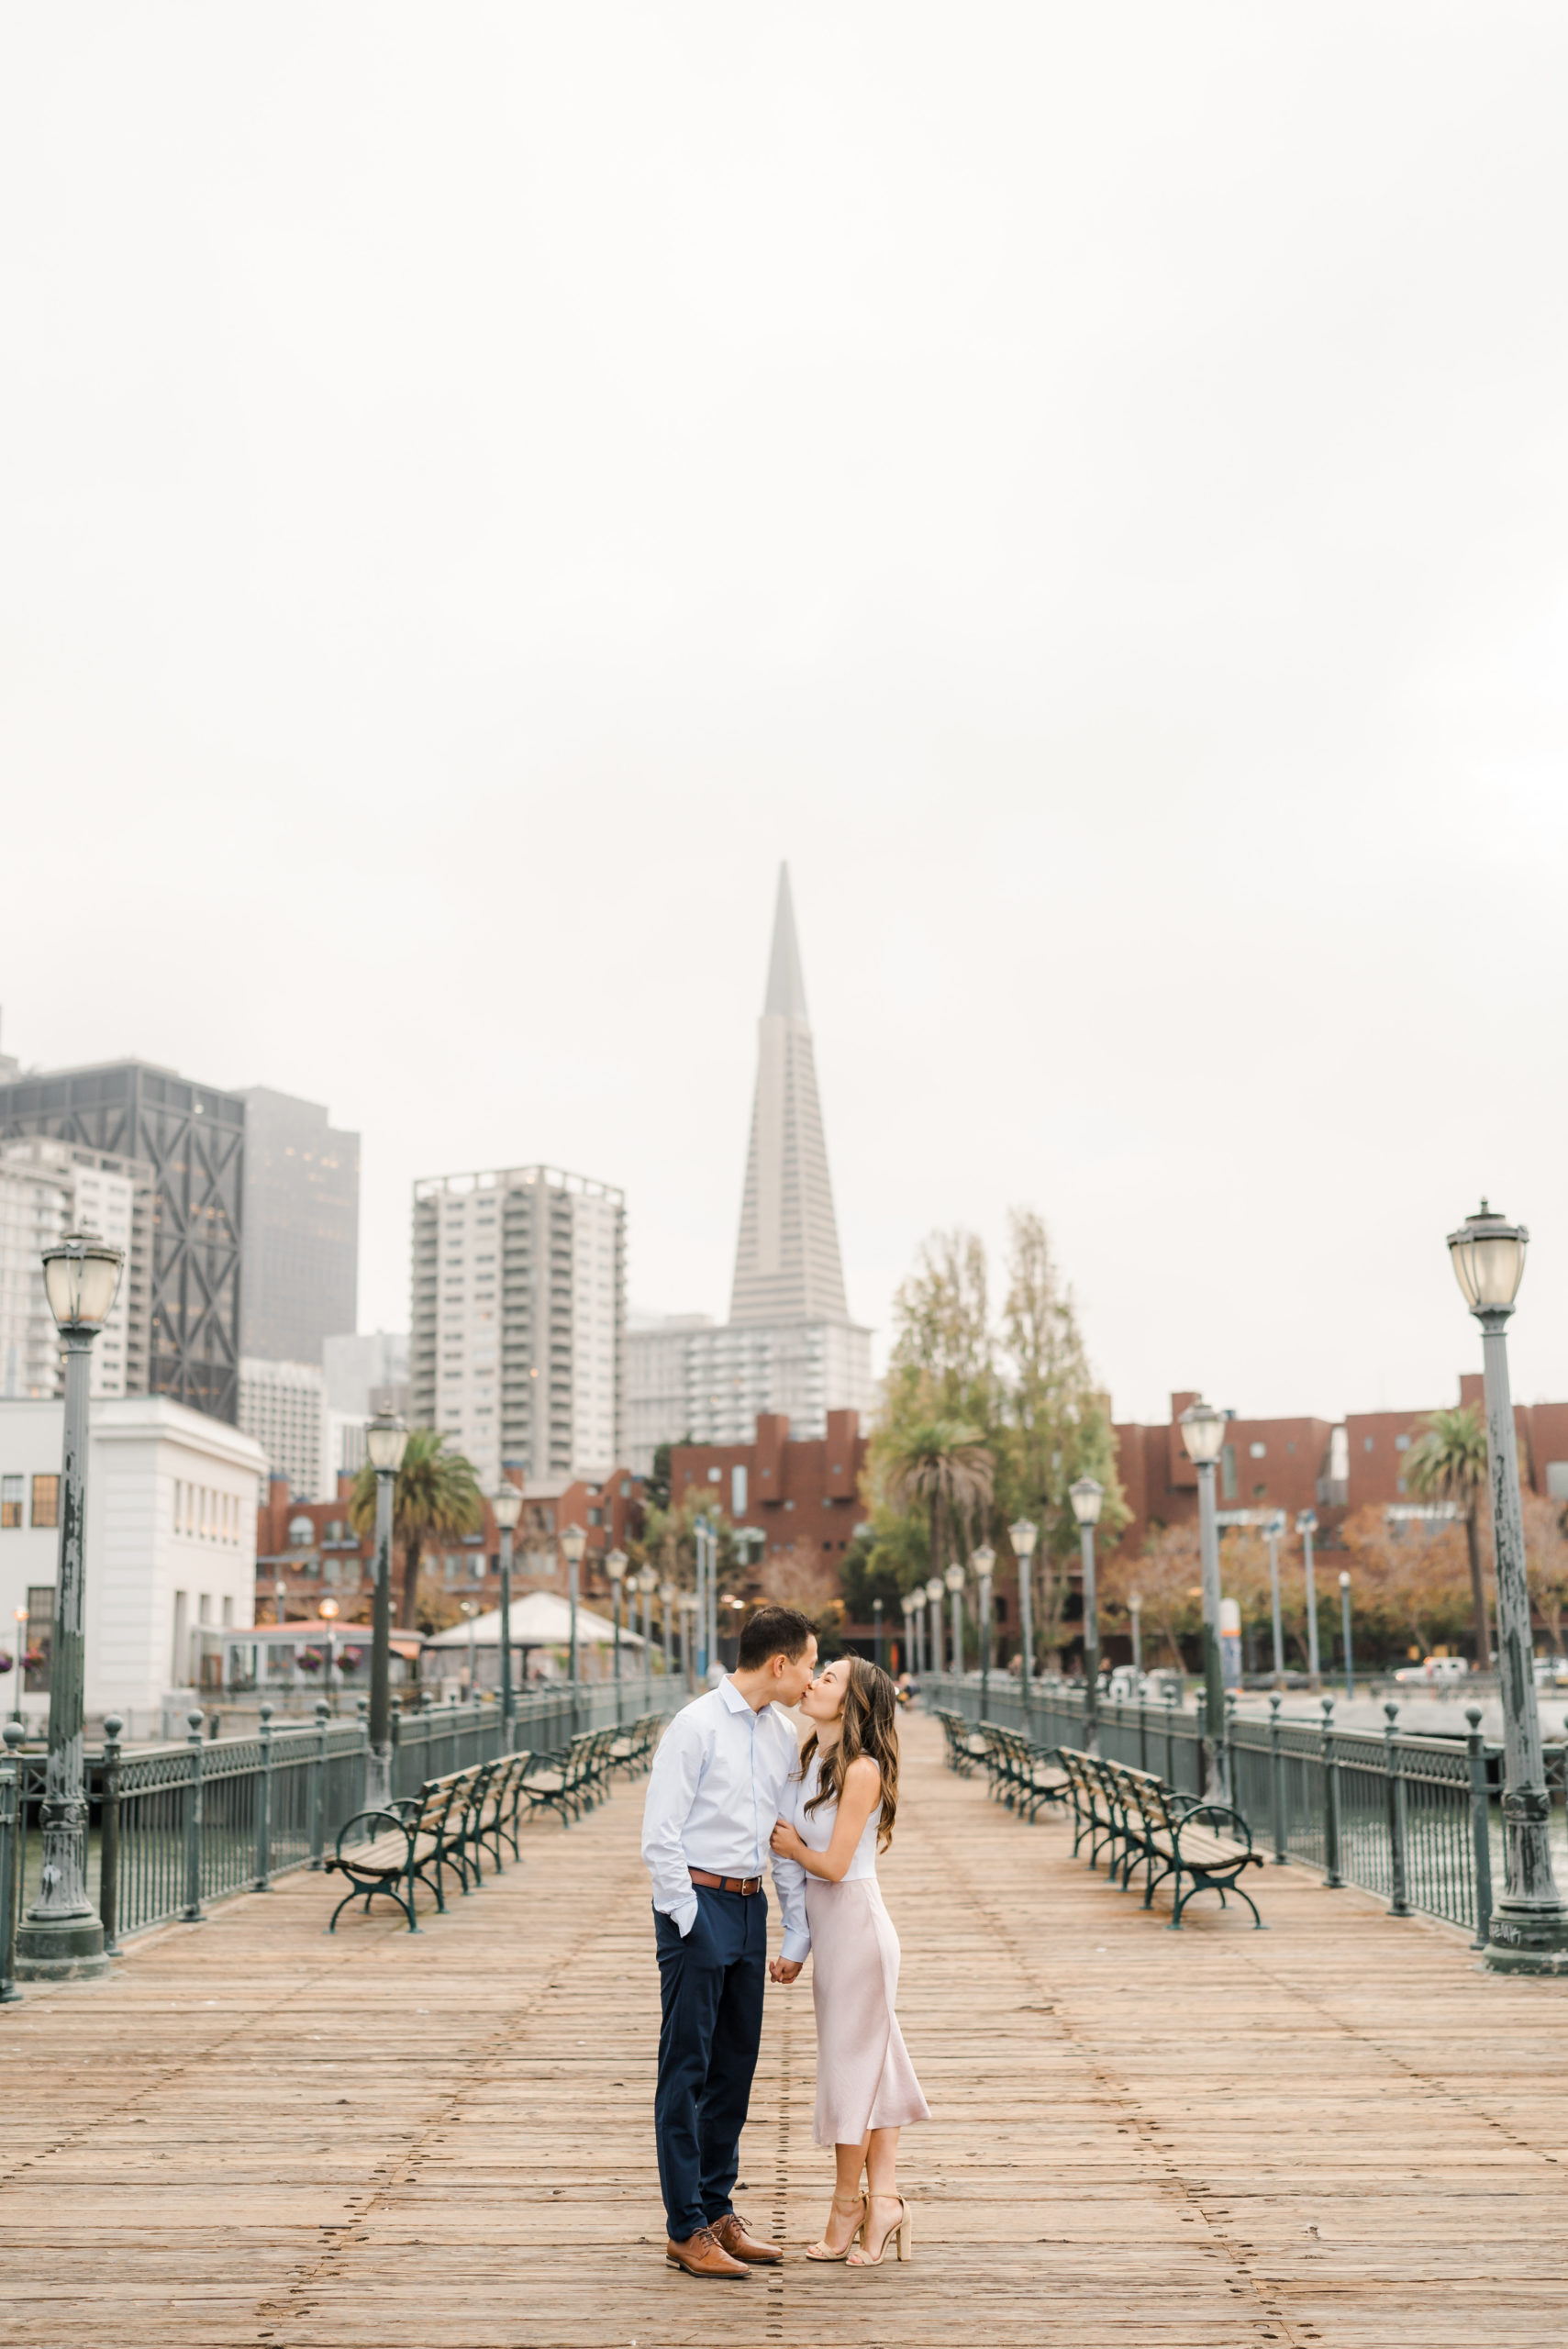
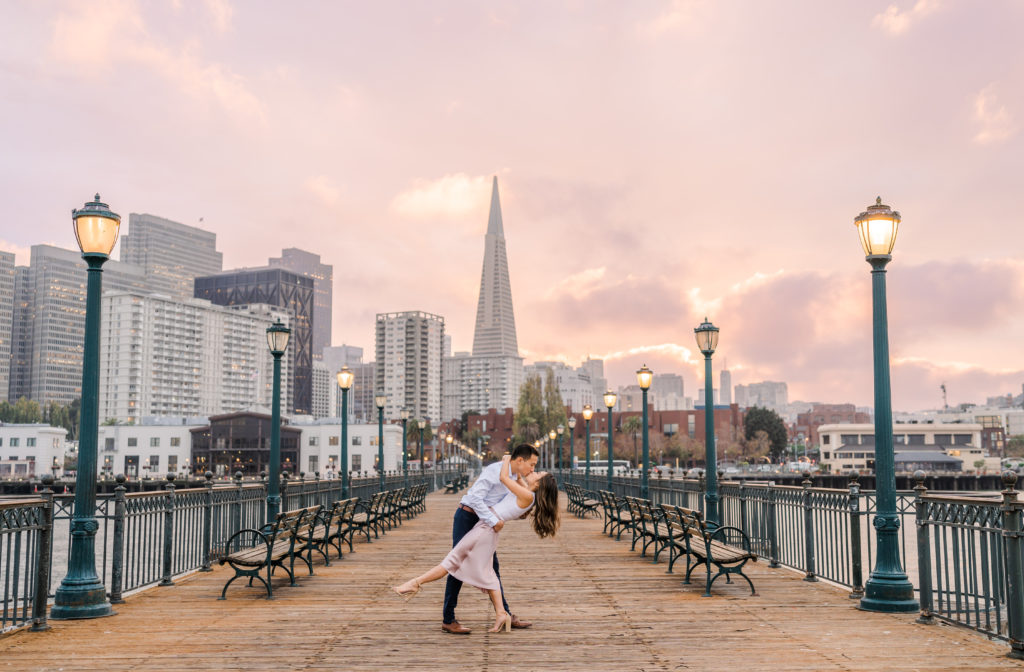
#6: PIER 7
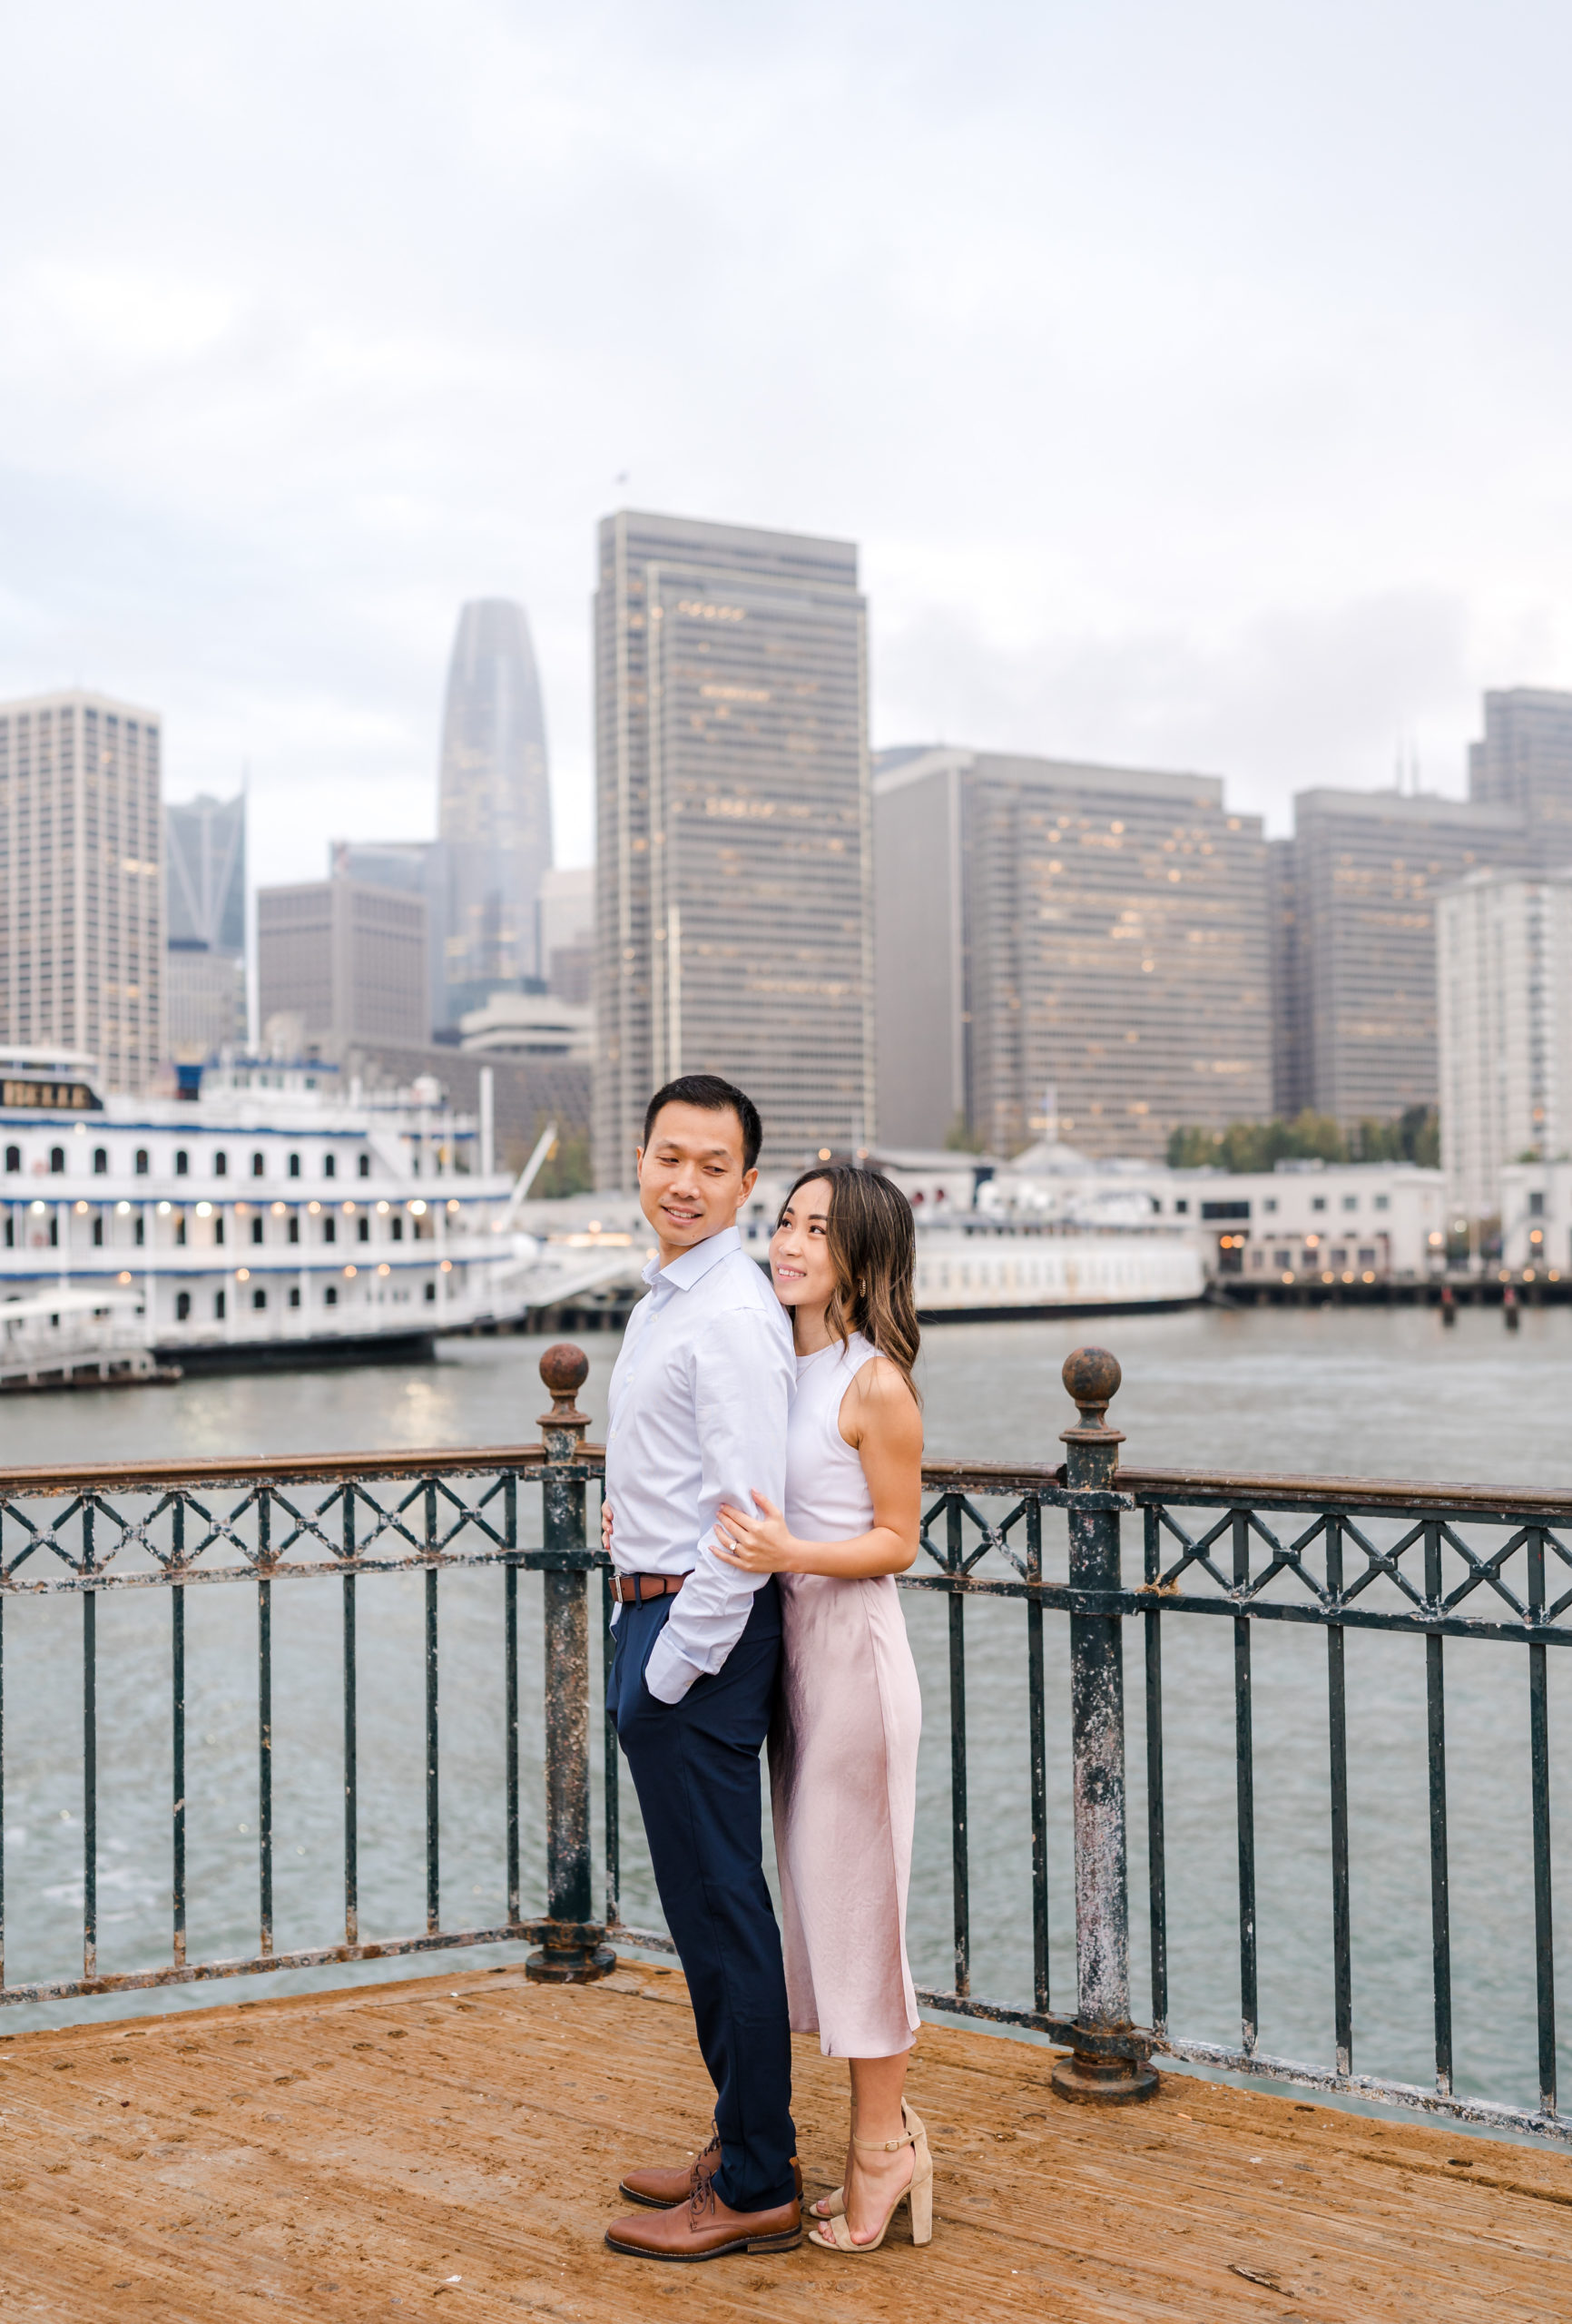
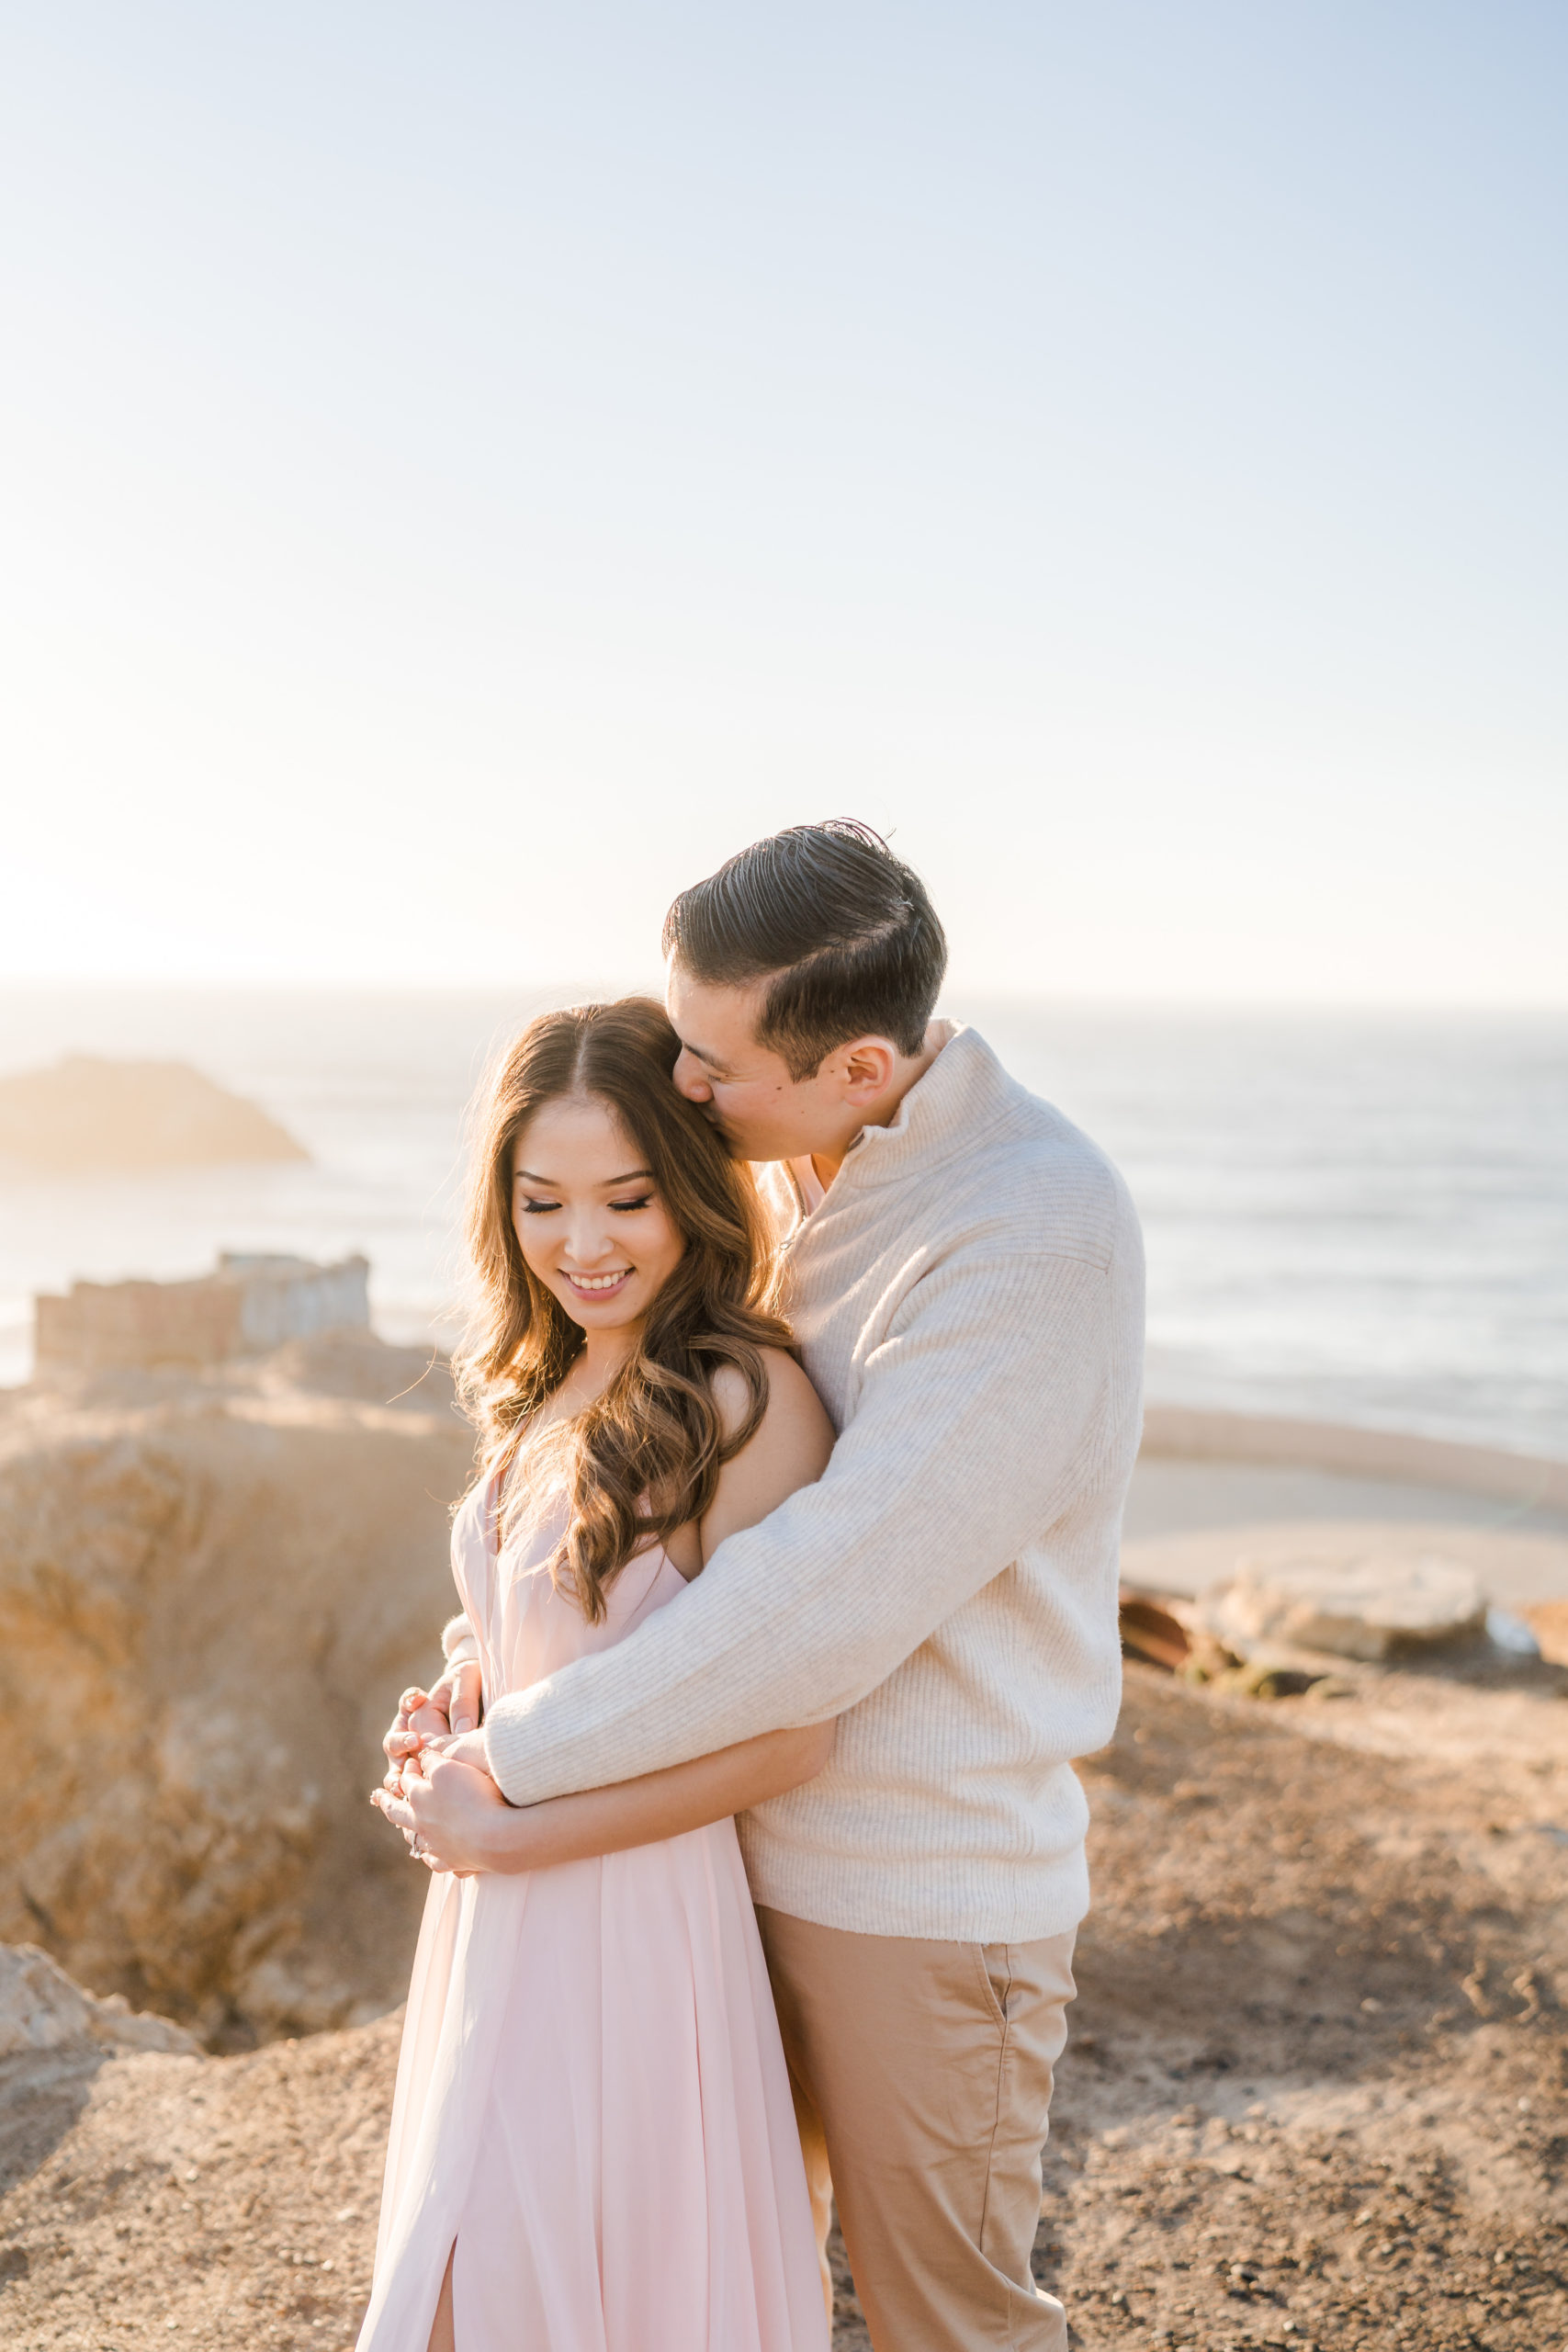
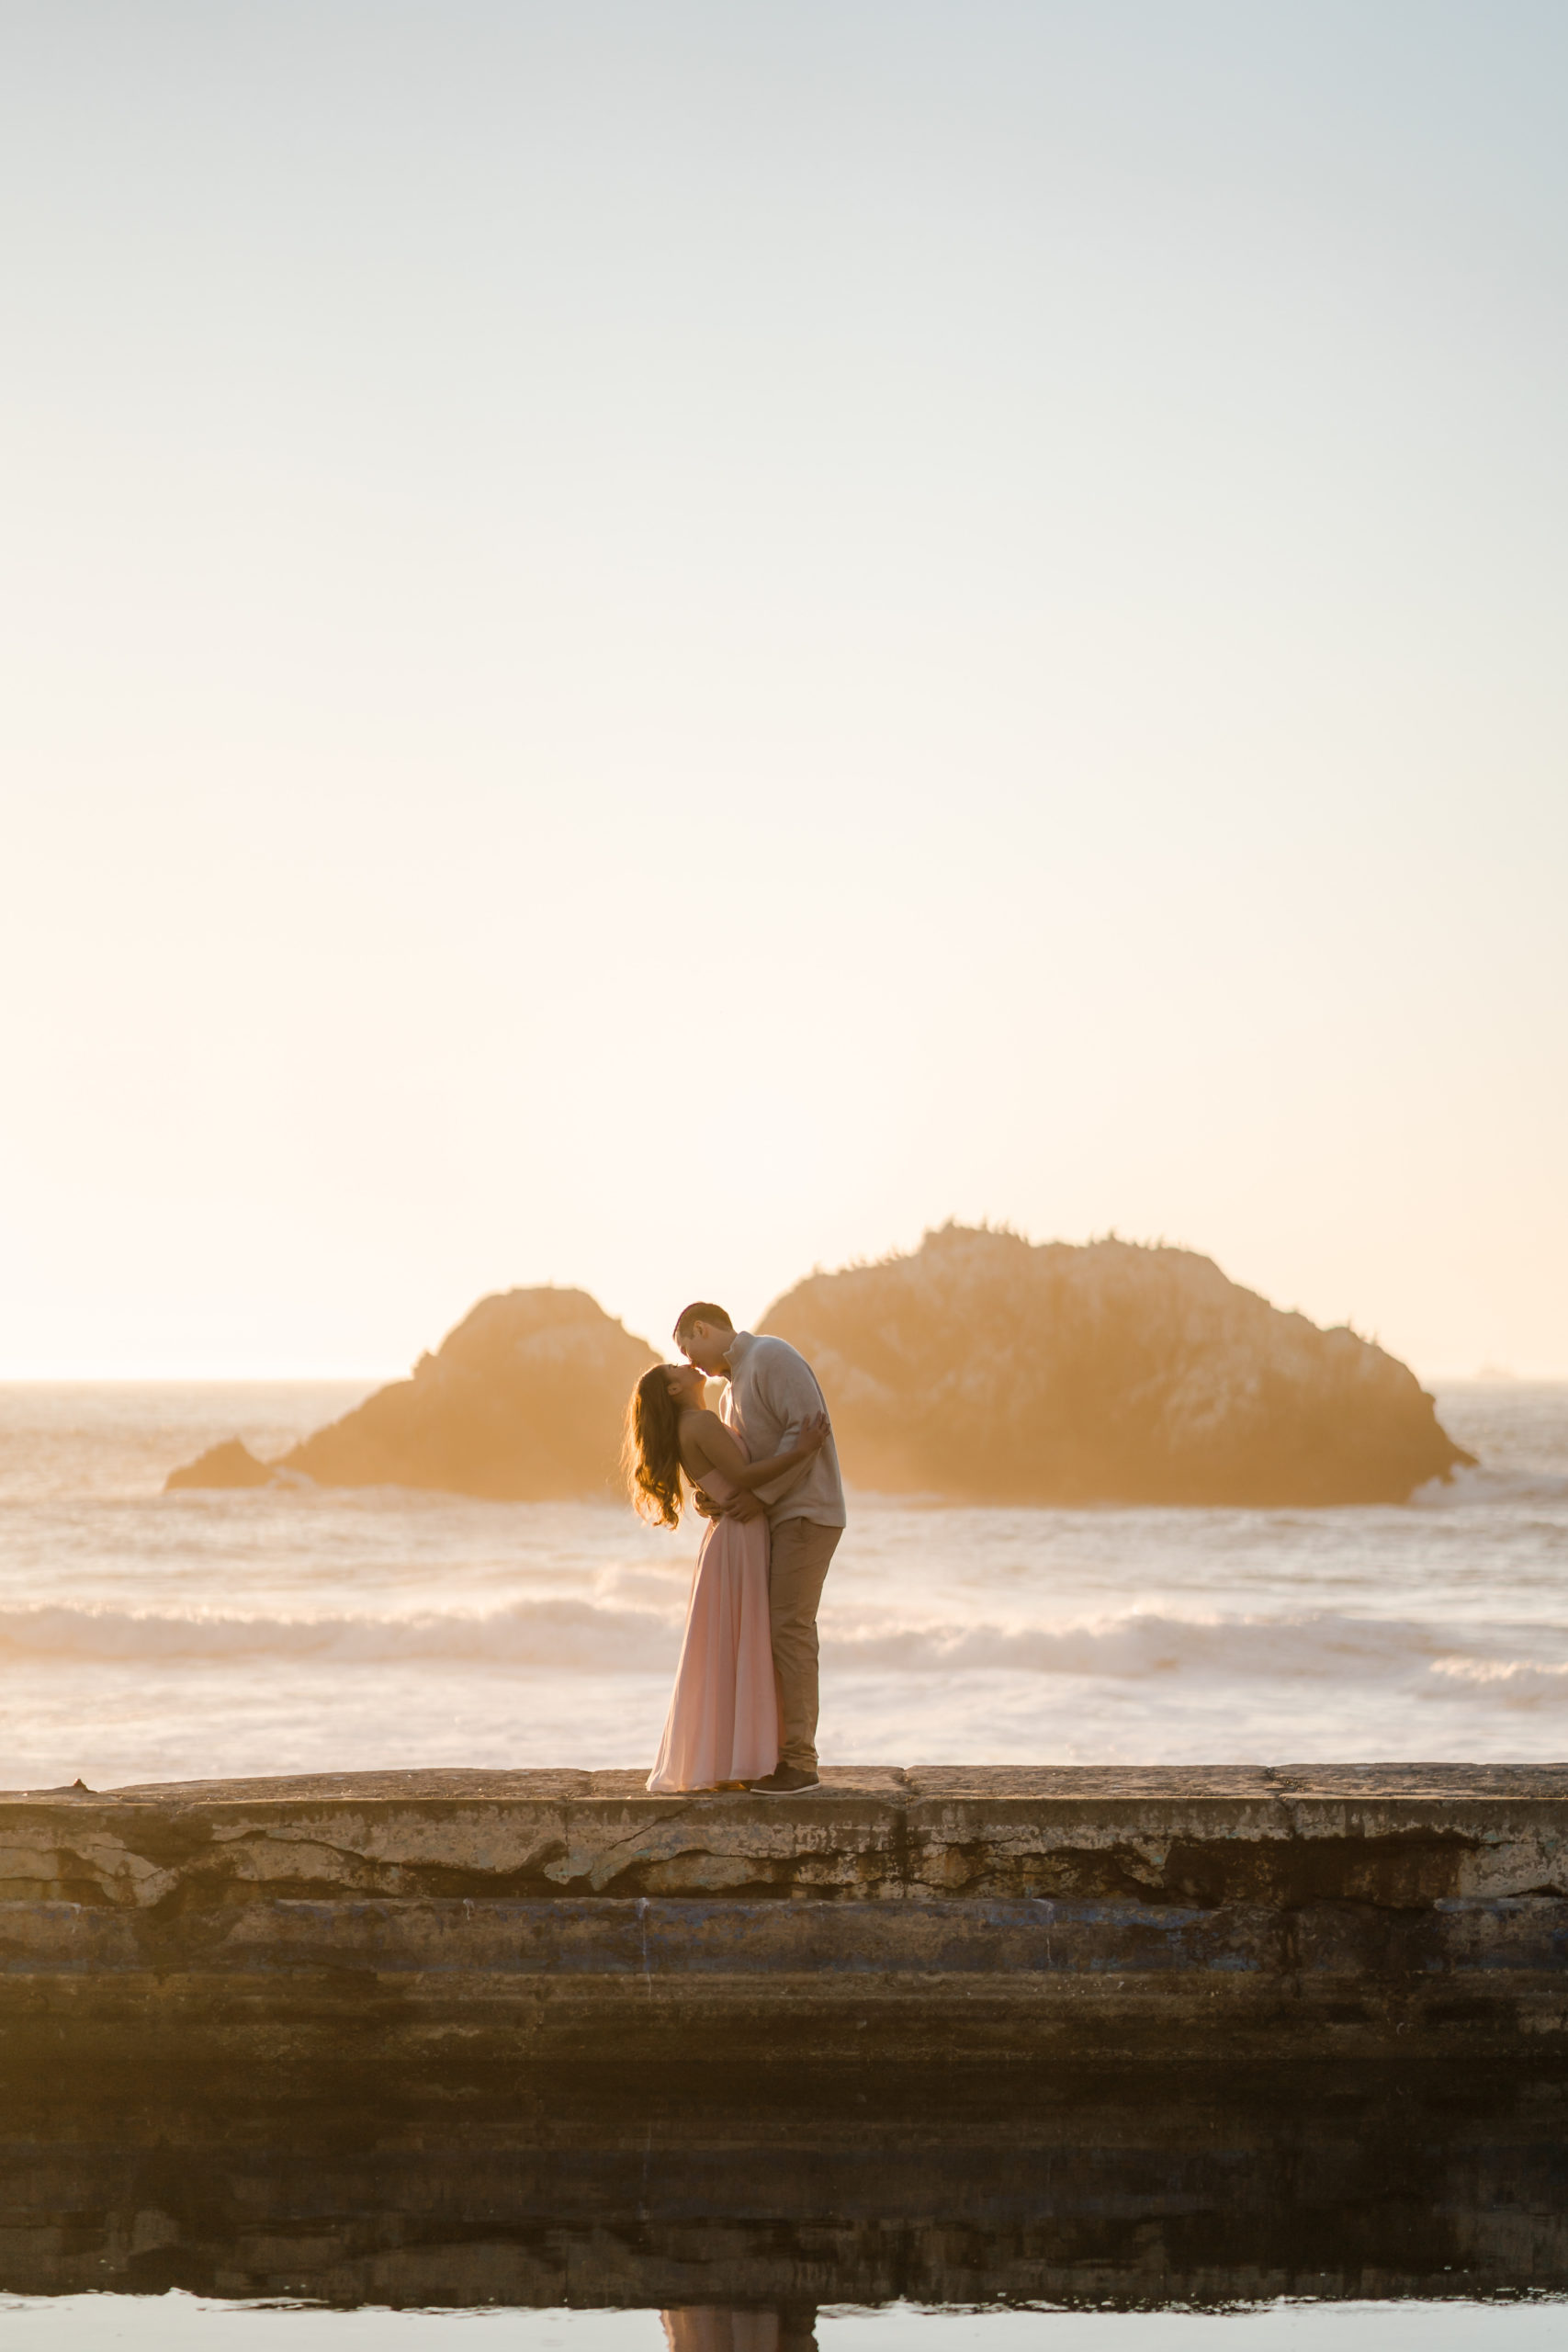
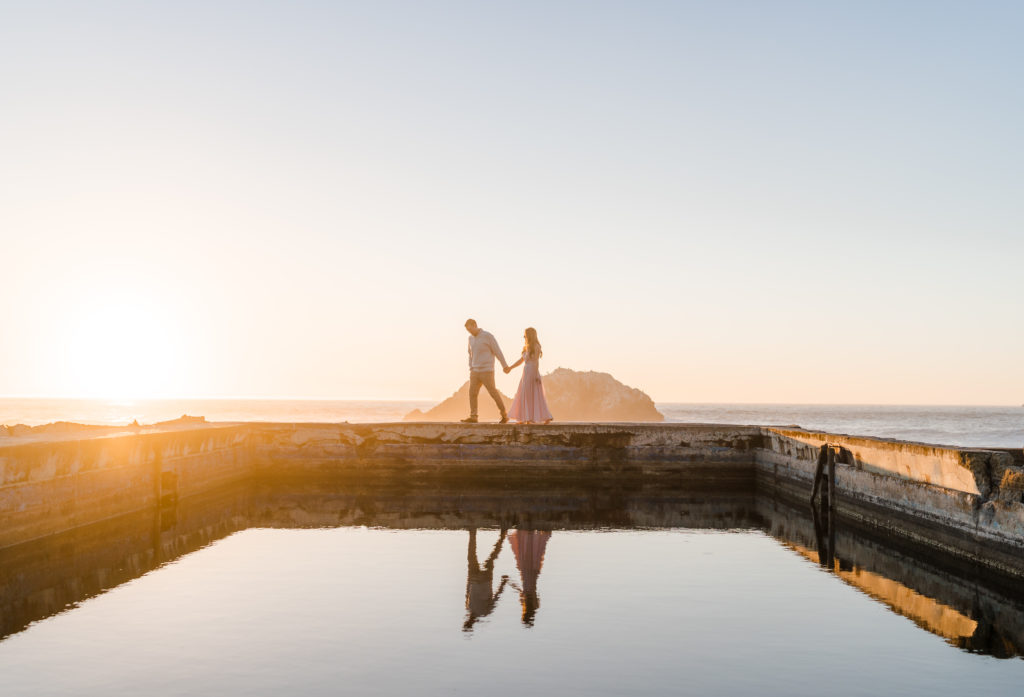
#7: SUTRO BATHS
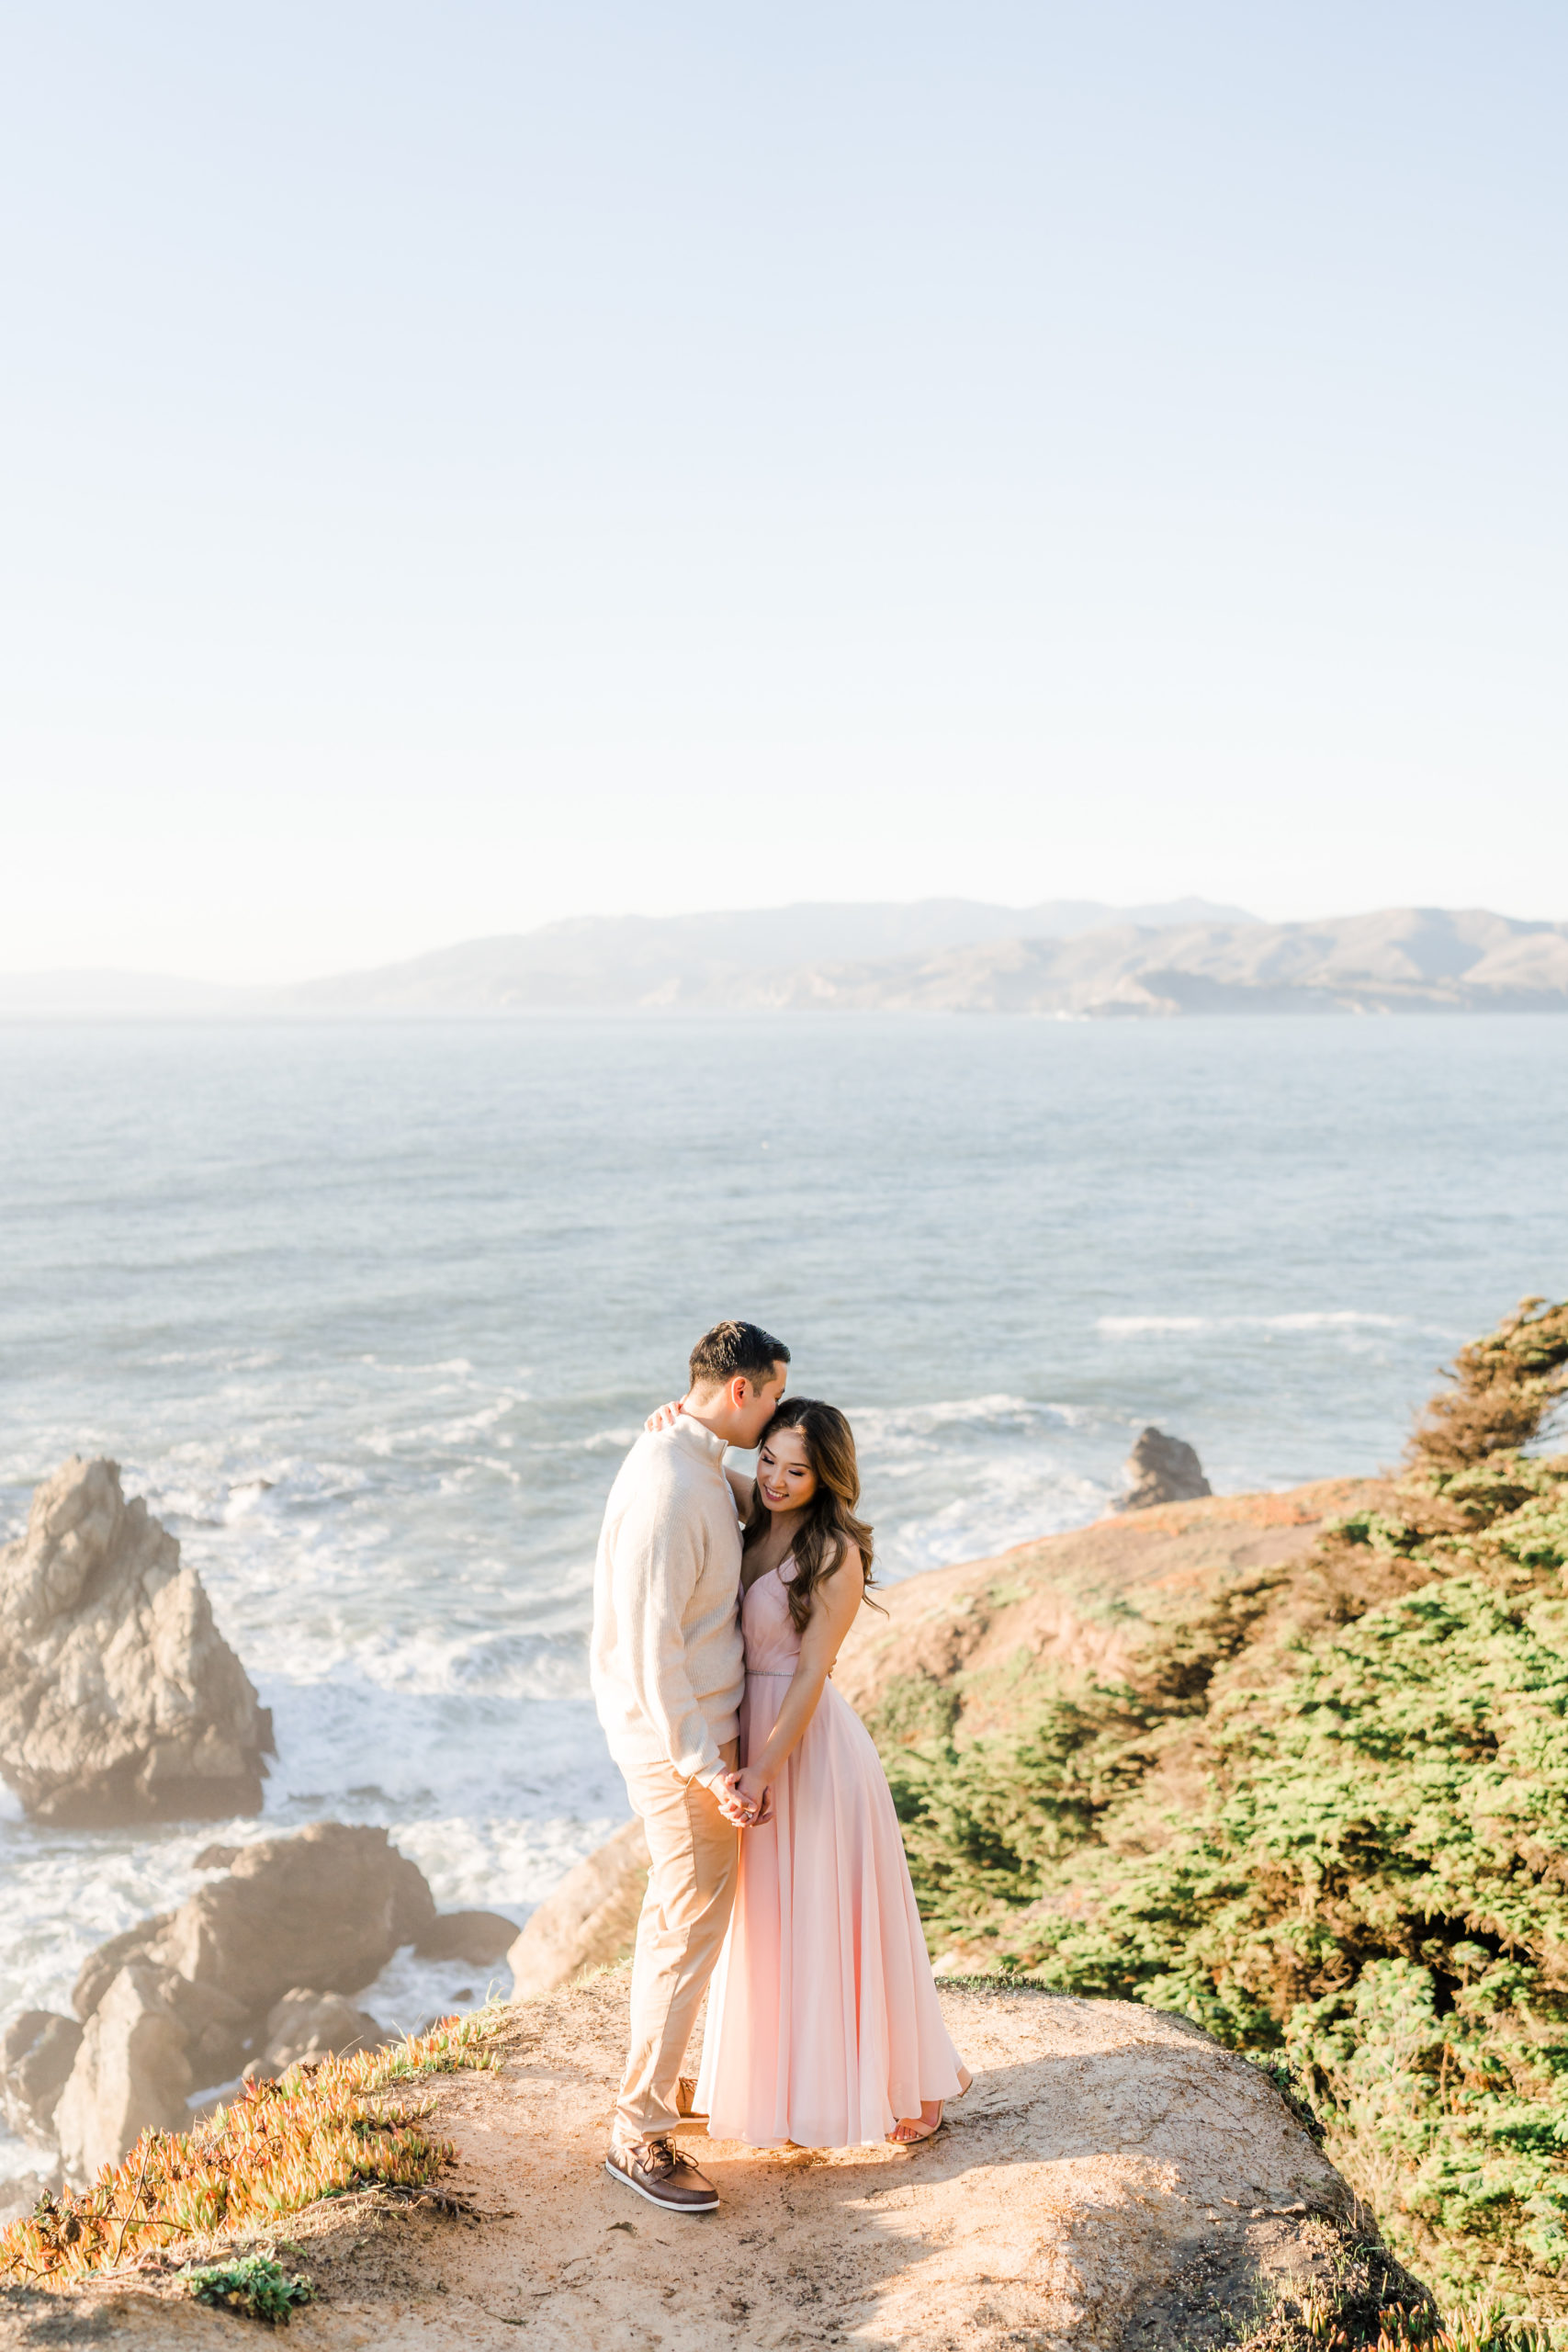
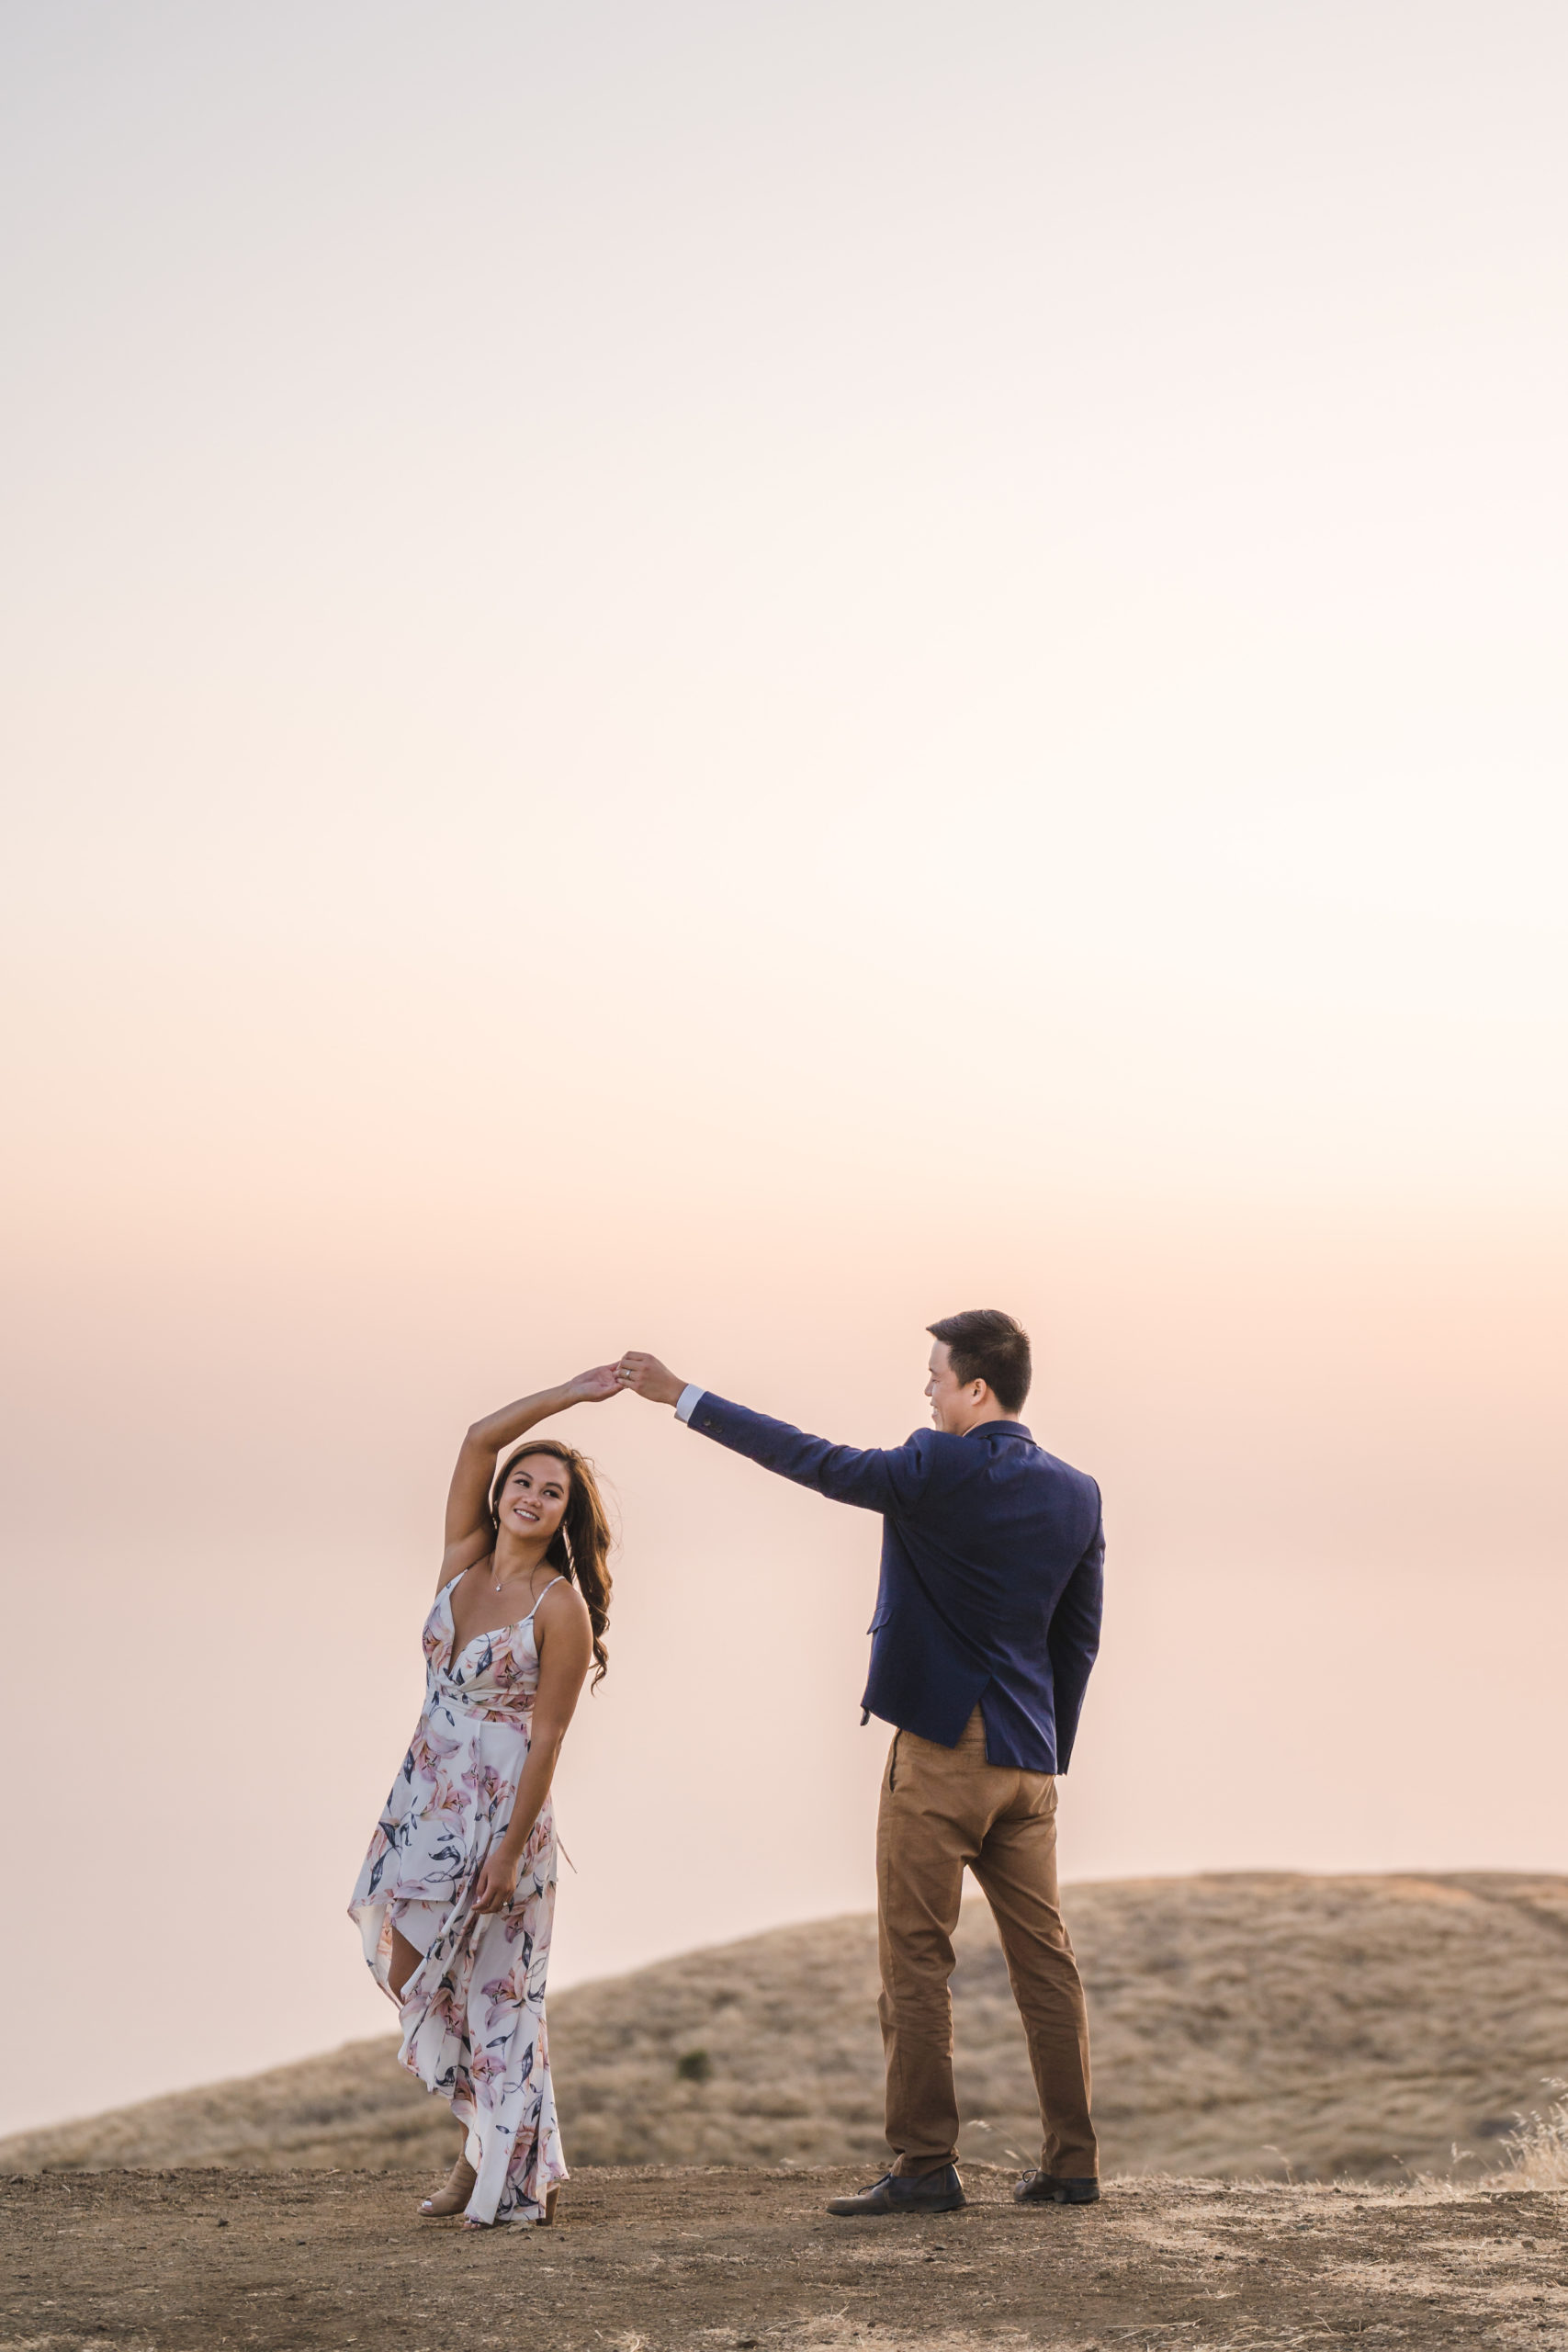
#8: MOUNT TAM


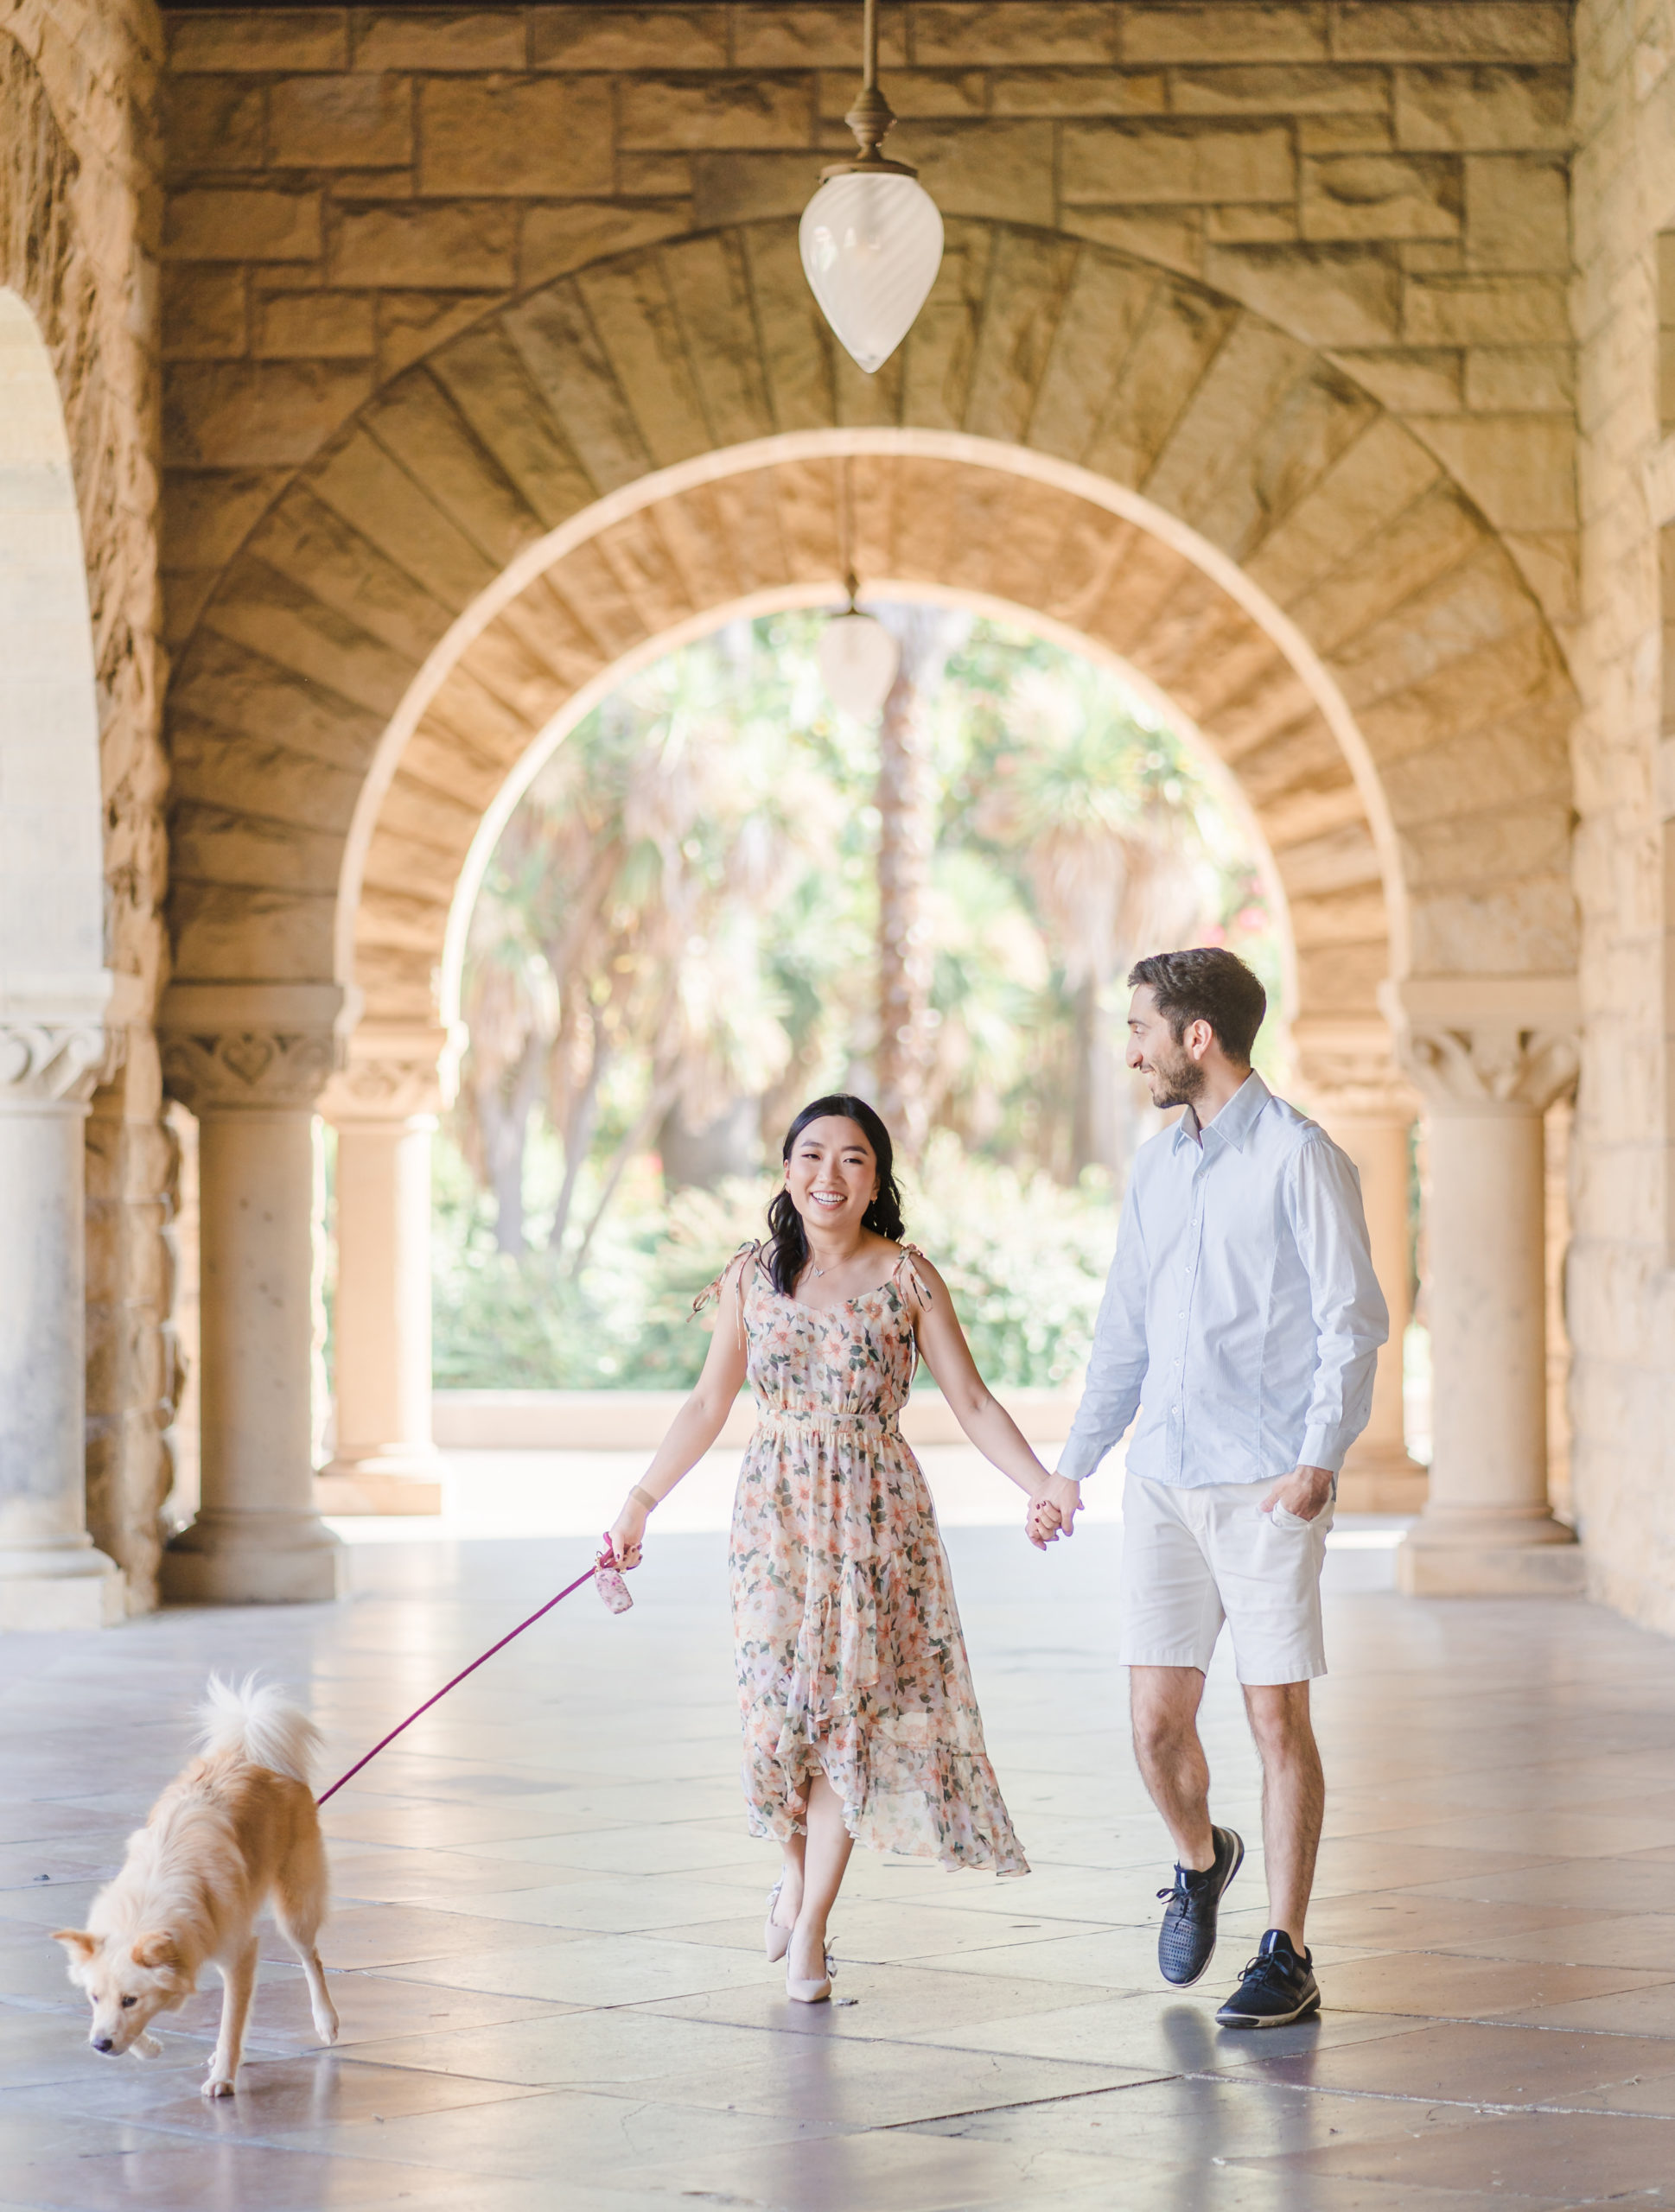
#9: GAMBLE GARDENS

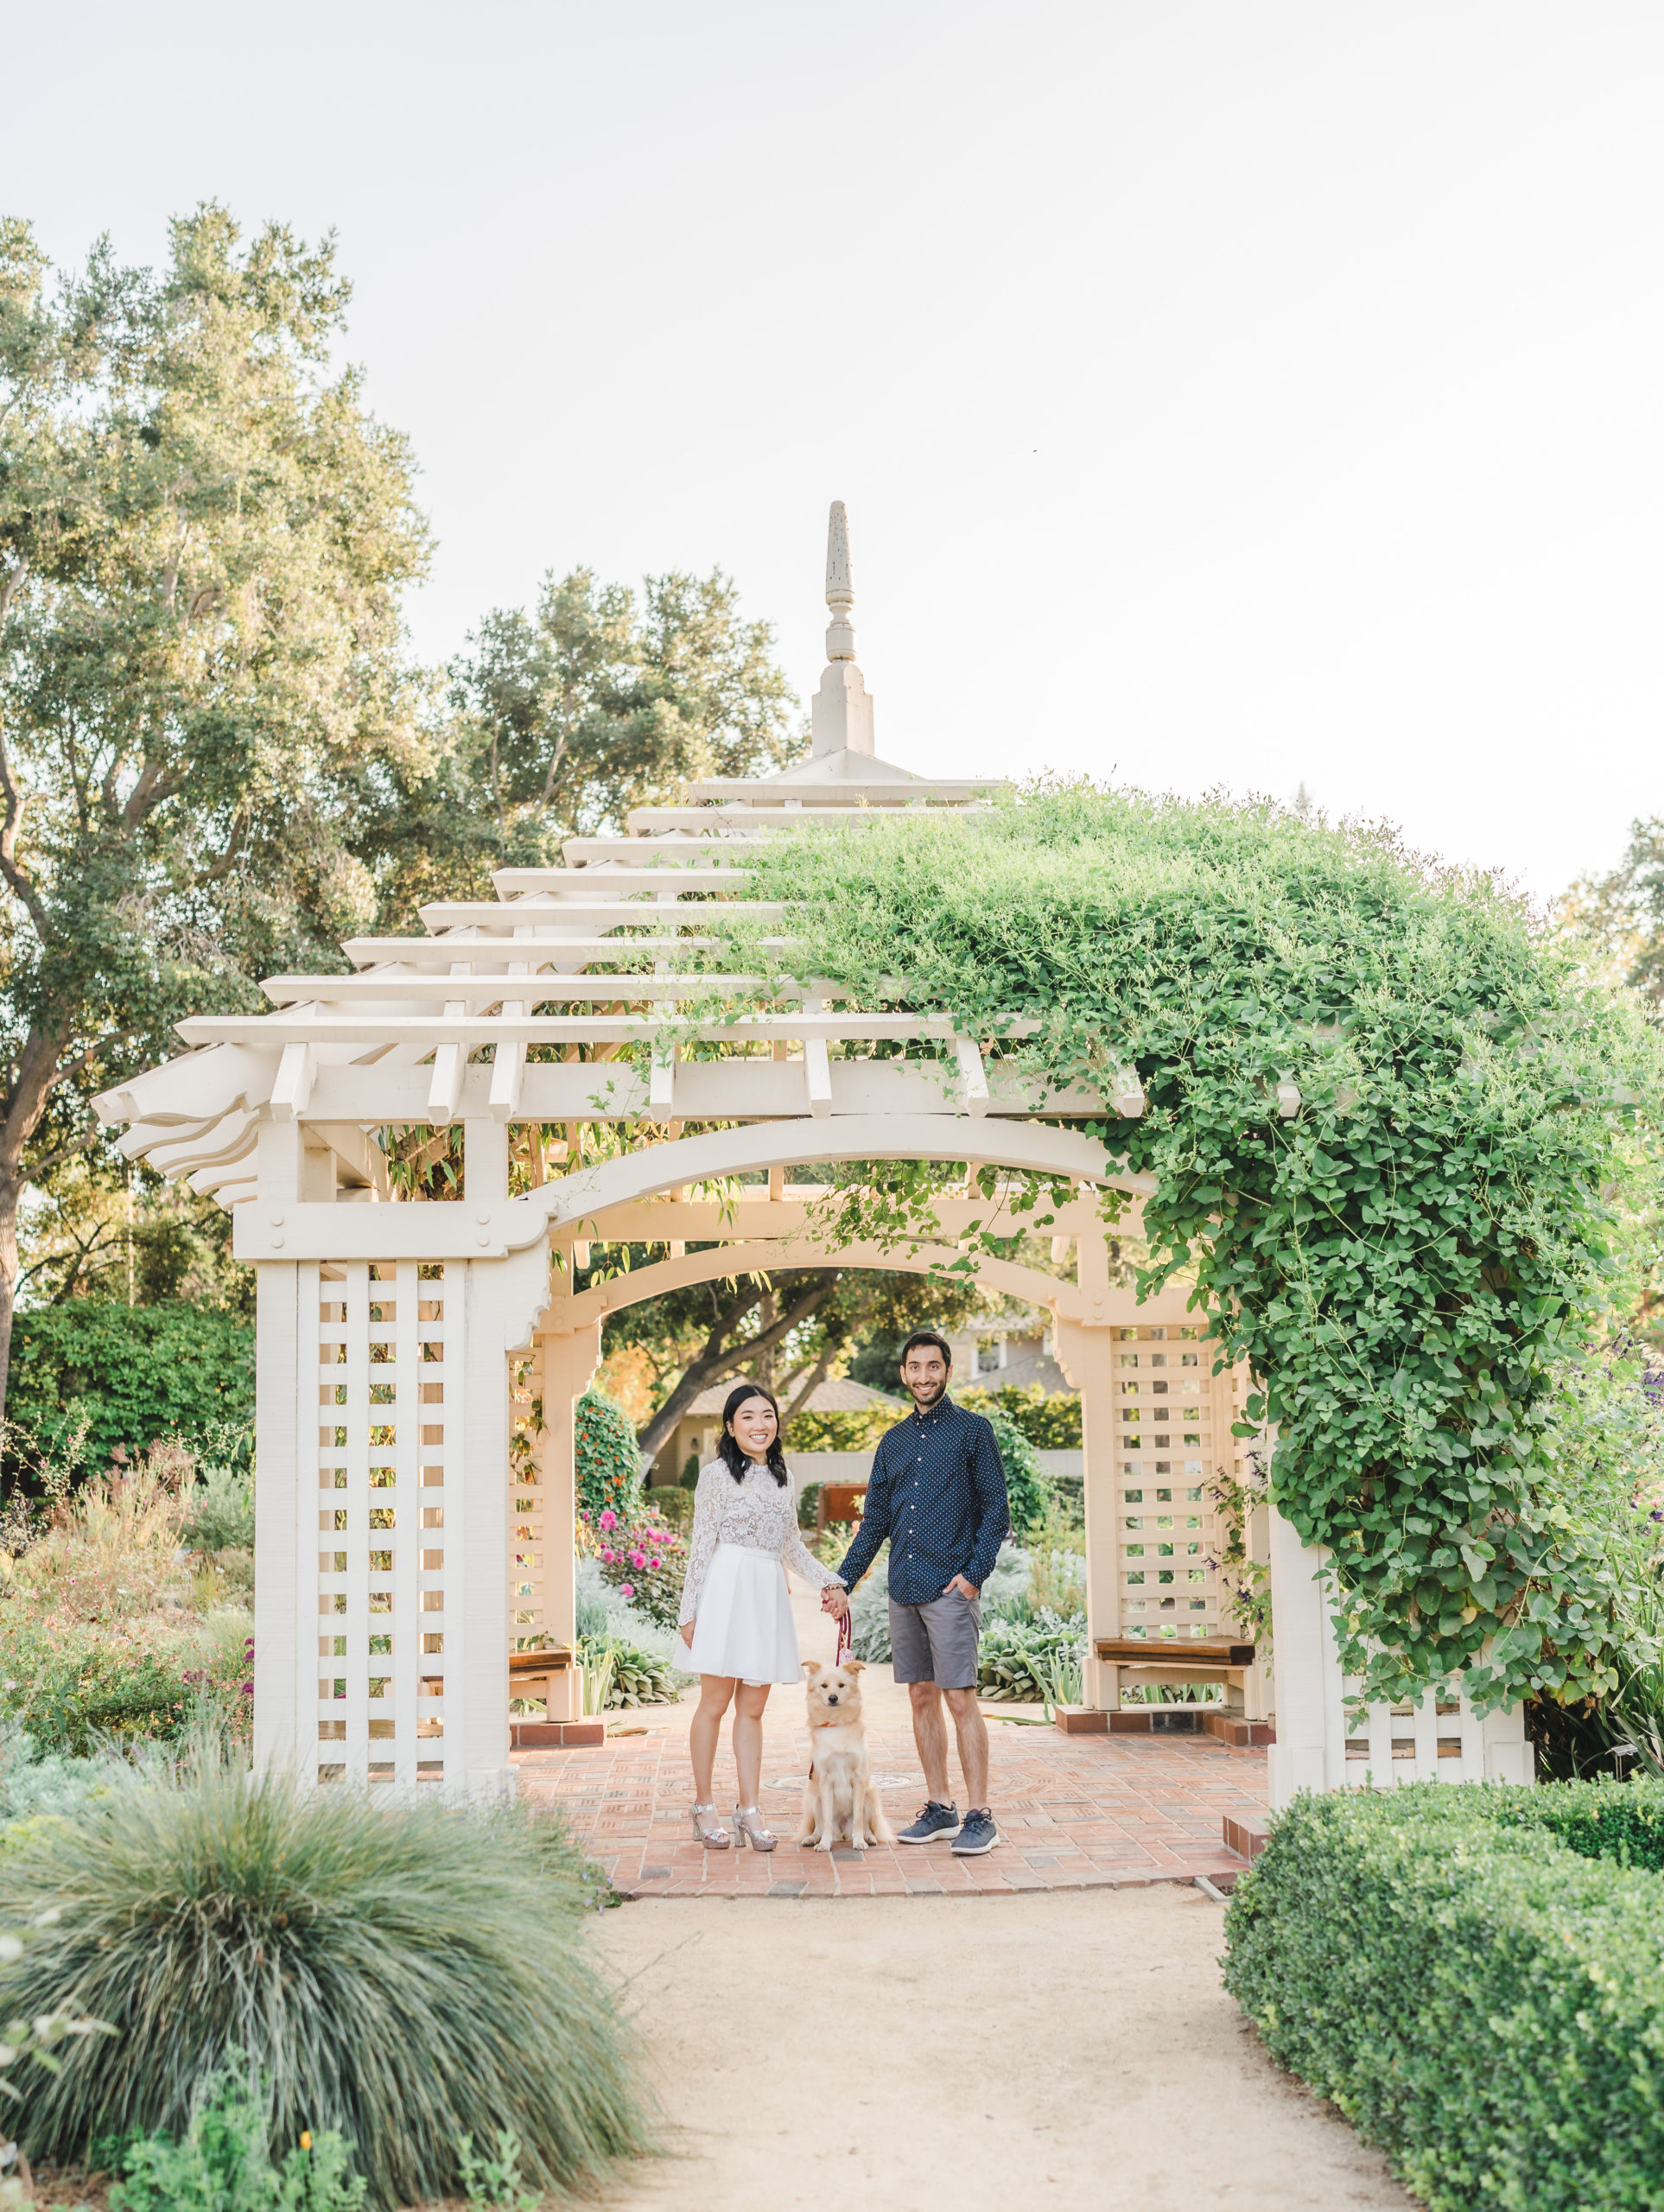
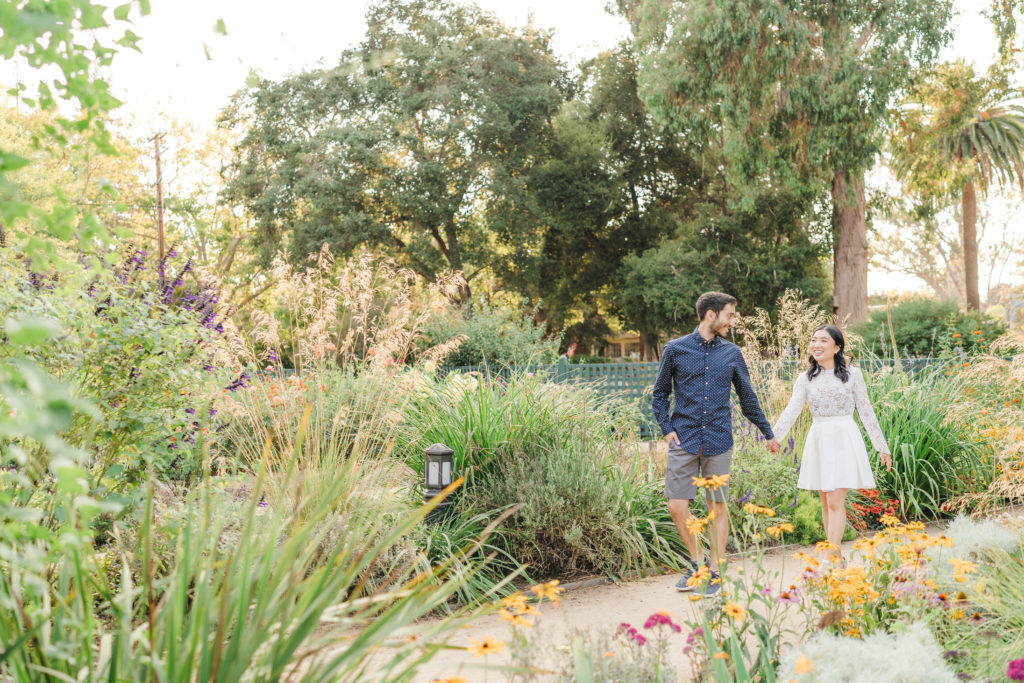
While there are so many more locations, these were some of the Best Locations for Scenic Photos in the Greater Bay Area! Do you have a favorite? If so, let me know!
ENJOYED THIS BLOG? CHECK OUT: Wedding Photographer’s Guide to a Bay Area Wedding
How CasinosMinimumDeposit Explains Low Deposit Thresholds in New Zealand
New Zealand’s online gambling market has undergone significant structural changes over the past decade, and one of the most visible shifts for everyday players has been the gradual reduction in minimum deposit requirements across licensed offshore platforms. Where operators once routinely set entry points at NZD 20 or even NZD 50, it is now common to find thresholds as low as NZD 1 or NZD 5. This shift is not accidental. It reflects a combination of payment technology evolution, competitive market pressure, changing player demographics, and the way independent research platforms have begun documenting and comparing these thresholds in granular detail. Understanding why these low deposit floors exist — and what they actually mean for players in New Zealand — requires looking at regulatory context, banking infrastructure, and the mechanics of how operators calculate risk against acquisition cost.
The Regulatory Environment Shaping Deposit Thresholds in New Zealand
New Zealand occupies an unusual position in global gambling law. The Gambling Act 2003 remains the primary legislative framework, and under its provisions, operating an online casino within New Zealand’s borders is prohibited for domestic companies. However, the law does not explicitly criminalise players for accessing offshore platforms, which has created a de facto open market where international operators serve New Zealand residents without meaningful legal obstruction. This ambiguity has had direct consequences for how operators structure their deposit policies when targeting New Zealand players.
Because no domestic licensing authority governs these offshore platforms in the New Zealand context, operators are not subject to local minimum deposit mandates. Instead, they apply policies shaped by their primary licensing jurisdiction — most commonly Malta (MGA), Gibraltar, Curaçao, or the Isle of Man. Malta Gaming Authority licensees, for instance, operate under a framework that emphasises responsible gambling tools, including deposit limits and self-exclusion mechanisms, but does not prescribe a minimum deposit floor. This regulatory gap means operators have considerable freedom to set thresholds based on commercial logic rather than compliance requirements.
The practical consequence is that the competitive market itself becomes the regulator of deposit thresholds. When one operator drops its minimum to NZD 5 and reports strong acquisition numbers from New Zealand, competitors follow. This race-to-accessibility dynamic has been particularly pronounced since approximately 2018, when mobile-first gambling became the dominant mode of play in the region. Mobile players, research consistently shows, prefer smaller, more frequent deposits rather than large single top-ups — a behavioural pattern that makes low deposit thresholds commercially rational for operators seeking to convert casual mobile browsers into registered accounts.
Responsible gambling considerations add another layer to this picture. The New Zealand Problem Gambling Foundation has long noted that lower deposit thresholds can serve protective functions when combined with appropriate limit-setting tools, because they allow players to maintain tighter control over their spending without needing to commit large sums upfront. However, the same thresholds can also lower the psychological barrier to entry for vulnerable players. This tension means that reputable offshore operators targeting New Zealand increasingly pair low minimums with mandatory responsible gambling disclosures and cooling-off period options — not because New Zealand law requires it, but because MGA and UKGC licensing standards, which many of these operators hold, demand it.
How Payment Infrastructure Enables and Constrains Minimum Deposits
The mechanics of why NZD 1 deposits are technically feasible in 2024, when they were not in 2010, come down almost entirely to payment processing costs. Traditional bank transfers and credit card transactions carry fixed processing fees that make very small transactions economically unviable for operators. A NZD 2 deposit processed through a major credit card network might generate a processing fee of NZD 0.30 to NZD 0.50 plus a percentage of the transaction — meaning the operator absorbs a cost representing 15 to 25 percent of the deposit before the player has placed a single bet. At that cost structure, minimum deposits below NZD 10 or NZD 15 were genuinely unprofitable to process.
The emergence of e-wallets — particularly Skrill and Neteller, both of which gained significant New Zealand user bases between 2012 and 2016 — began shifting this calculus. E-wallet transactions carry lower per-transaction fixed costs because the payment processor has already absorbed the bank-to-wallet transfer cost, and the casino-to-wallet leg is an internal ledger movement at scale. This allowed operators to reduce minimums for e-wallet deposits specifically, which is why many platforms began advertising NZD 10 minimums for e-wallets while maintaining NZD 20 or NZD 30 minimums for card deposits.
The more transformative development came with cryptocurrency adoption and, separately, with the rise of instant banking solutions like POLi, which connects directly to New Zealand bank accounts without card network intermediaries. POLi, despite its eventual discontinuation in 2023 after Westpac and other major banks withdrew support, demonstrated that direct bank connectivity could dramatically reduce processing friction. Its successor services and the broader ecosystem of open banking APIs have continued this trend. Cryptocurrency deposits — particularly Bitcoin and Ethereum — carry network fees that are independent of transaction size, meaning a NZD 1 crypto deposit is technically as feasible to process as a NZD 1,000 one, though exchange rate volatility introduces its own complications.
Research aggregators that track these conditions across dozens of platforms provide a useful function here. The database maintained at http://casinos-minimum-deposit.com/ catalogues current minimum deposit requirements by payment method and jurisdiction, which illustrates clearly how the NZD minimum varies not just between operators but between payment channels within the same operator. A platform might list NZD 10 as its headline minimum while offering NZD 1 deposits via specific cryptocurrency wallets — a distinction that generic casino review sites frequently miss but that materially affects a player’s actual access point.
The arrival of Buy Now Pay Later services in New Zealand’s broader e-commerce ecosystem — Afterpay launched in New Zealand in 2015 and reached significant market penetration by 2019 — briefly raised questions about whether similar instalment-based payment logic might enter gambling. Most operators and payment processors have avoided this integration, partly due to responsible gambling concerns and partly because BNPL providers explicitly exclude gambling in their merchant terms. However, the broader normalisation of micro-transaction culture that BNPL accelerated has influenced player expectations around deposit granularity, contributing to demand for lower thresholds even on conventional payment methods.
What CasinosMinimumDeposit Tracks and Why Methodology Matters
Independent comparison platforms occupy a specific role in the New Zealand gambling information ecosystem. Because no domestic regulator publishes comparative data on offshore operator terms, players rely on third-party research to understand what deposit conditions actually apply to them. CasinosMinimumDeposit approaches this through a methodology that distinguishes between advertised minimums and verified minimums — a distinction that turns out to be significant in practice.
Advertised minimums are what operators list in their terms and conditions or on their cashier pages at the time of account creation. Verified minimums are what researchers confirm through actual deposit testing, which sometimes reveals discrepancies. An operator might list NZD 10 as its minimum but apply a NZD 20 floor specifically to New Zealand bank card transactions due to a regional payment processor agreement. Conversely, some platforms list higher minimums in their general terms but apply lower thresholds automatically to accounts that use specific e-wallets or have completed identity verification.
The verification methodology also accounts for currency conversion. New Zealand players depositing in NZD on platforms that operate primarily in USD or EUR face conversion at the point of deposit, and the effective minimum in NZD terms fluctuates with exchange rates. A platform advertising a USD 1 minimum deposit translates to approximately NZD 1.60 to NZD 1.70 at mid-2024 exchange rates, but this figure changes meaningfully over a 12-month period. Platforms that track these figures in real time provide more accurate guidance than those that publish static conversion tables updated quarterly.
CasinosMinimumDeposit also documents the relationship between minimum deposit thresholds and bonus eligibility, which is where many players encounter unexpected friction. A platform might offer a welcome bonus that requires a minimum NZD 20 deposit to activate, while the platform’s general minimum deposit is NZD 5. A player who deposits NZD 5 can play, but receives no bonus. This layering of thresholds — operational minimum versus bonus-qualifying minimum — is a structural feature of almost every major offshore operator and one that comparison platforms need to document separately rather than conflating the two figures.
The tracking of threshold changes over time is another methodologically important function. Between 2020 and 2023, the average verified minimum deposit across platforms actively targeting New Zealand players dropped by approximately 35 to 40 percent, according to data compiled by researchers in this space. This decline correlates with the cryptocurrency integration wave of 2020 to 2021, when many operators added crypto payment options specifically because they enabled lower practical minimums without increasing card processing costs. Understanding this trajectory helps players anticipate where minimums are likely to go — and helps operators understand competitive positioning.
Player Behaviour and the Practical Implications of Low Thresholds
The existence of low deposit thresholds changes player behaviour in ways that are empirically documented but not always intuitively obvious. The most significant effect is on session frequency rather than session size. Research from European markets — which provide the most rigorous gambling behaviour data given the presence of nationally licensed and regulated operators required to report player statistics — consistently shows that players with access to NZD 5 or NZD 10 minimums make deposits approximately three to four times more frequently than those whose lowest accessible threshold is NZD 20 or NZD 30. Total monthly spend is often similar, but the distribution across sessions is more granular.
This has implications for responsible gambling. More frequent, smaller deposits can indicate a player who is maintaining tighter budget control — topping up deliberately rather than loading a large sum and playing until it is exhausted. It can equally indicate a player who is chasing losses in smaller increments, which some researchers argue is a more insidious pattern because the individual transactions feel less significant. The New Zealand Problem Gambling Foundation’s 2022 annual report noted that the shift toward micro-deposit behaviour in online gambling warranted further longitudinal study, though it stopped short of recommending minimum deposit floors as a policy tool.
For operators, low thresholds serve as acquisition tools more than revenue drivers. The economics of a NZD 1 deposit are not attractive in isolation — the operator’s customer acquisition cost for a new player typically runs between NZD 30 and NZD 80 when marketing spend is factored in, meaning a NZD 1 first deposit represents a deeply loss-making transaction. The logic is that a player who makes a NZD 1 first deposit to test a platform is more likely to return and make larger deposits once they are comfortable with the interface, payment processing speed, and game quality. The low threshold reduces the commitment required for the initial evaluation, functioning as a trial mechanism rather than a meaningful revenue event.
This trial function is particularly relevant in the New Zealand context because New Zealand players have historically shown strong brand loyalty once a platform relationship is established. Survey data from the New Zealand Racing Board’s gambling participation studies (conducted periodically since 2012) suggests that New Zealand online gamblers use fewer platforms simultaneously than their Australian or British counterparts, preferring to concentrate activity on one or two trusted operators. Lowering the initial commitment required to establish that trust relationship is therefore strategically rational for operators seeking long-term player value rather than short-term deposit volume.
The interaction between low minimums and loyalty programmes also deserves attention. Many offshore platforms targeting New Zealand operate tiered VIP or loyalty schemes where points accumulate based on wagering volume. A player who begins with NZD 1 deposits and gradually increases their deposit frequency and size as platform familiarity grows is precisely the player these schemes are designed to capture. The low threshold is the entry point to a retention architecture that, at its upper tiers, involves personalised account management, cashback arrangements, and deposit bonuses that are not publicly advertised. Understanding this architecture helps players make more informed decisions about which platforms offer genuine long-term value versus those using low thresholds purely as acquisition bait without corresponding retention quality.
The New Zealand gambling landscape will continue evolving as the government periodically revisits the Gambling Act 2003’s application to offshore operators. A 2021 Department of Internal Affairs review raised the possibility of a licensing framework for offshore operators serving New Zealand residents — a development that, if implemented, would likely introduce formal minimum deposit regulations for the first time. Until such a framework exists, the combination of competitive market dynamics, payment technology development, and independent research platforms documenting actual conditions will remain the primary forces shaping what deposit thresholds New Zealand players encounter in practice. Players who understand the structural reasons behind these thresholds are better positioned to use them to their advantage — testing platforms at minimal financial risk while maintaining the kind of disciplined approach to bankroll management that makes online gambling a sustainable leisure activity rather than a financial liability.


[…] Did you enjoy these dreamy Marin Headlands Engagements? CHECK OUT MY PREVIOUS BLOG: BEST LOCATIONS FOR SCENIC PHOTOS IN THE GREATER BAY AREA. […]